Getting a car loan requires a stable and
sufficient monthly income. It is a dream for many, but a low CIBIL score
shouldn't come in the way of buying your first car. When one thinks of their
first car, they are probably having thoughts like "I need it" or "I
deserve it." A car makes your life much easier; the crowd is less
significant, and commuting in rain becomes hassle-free.
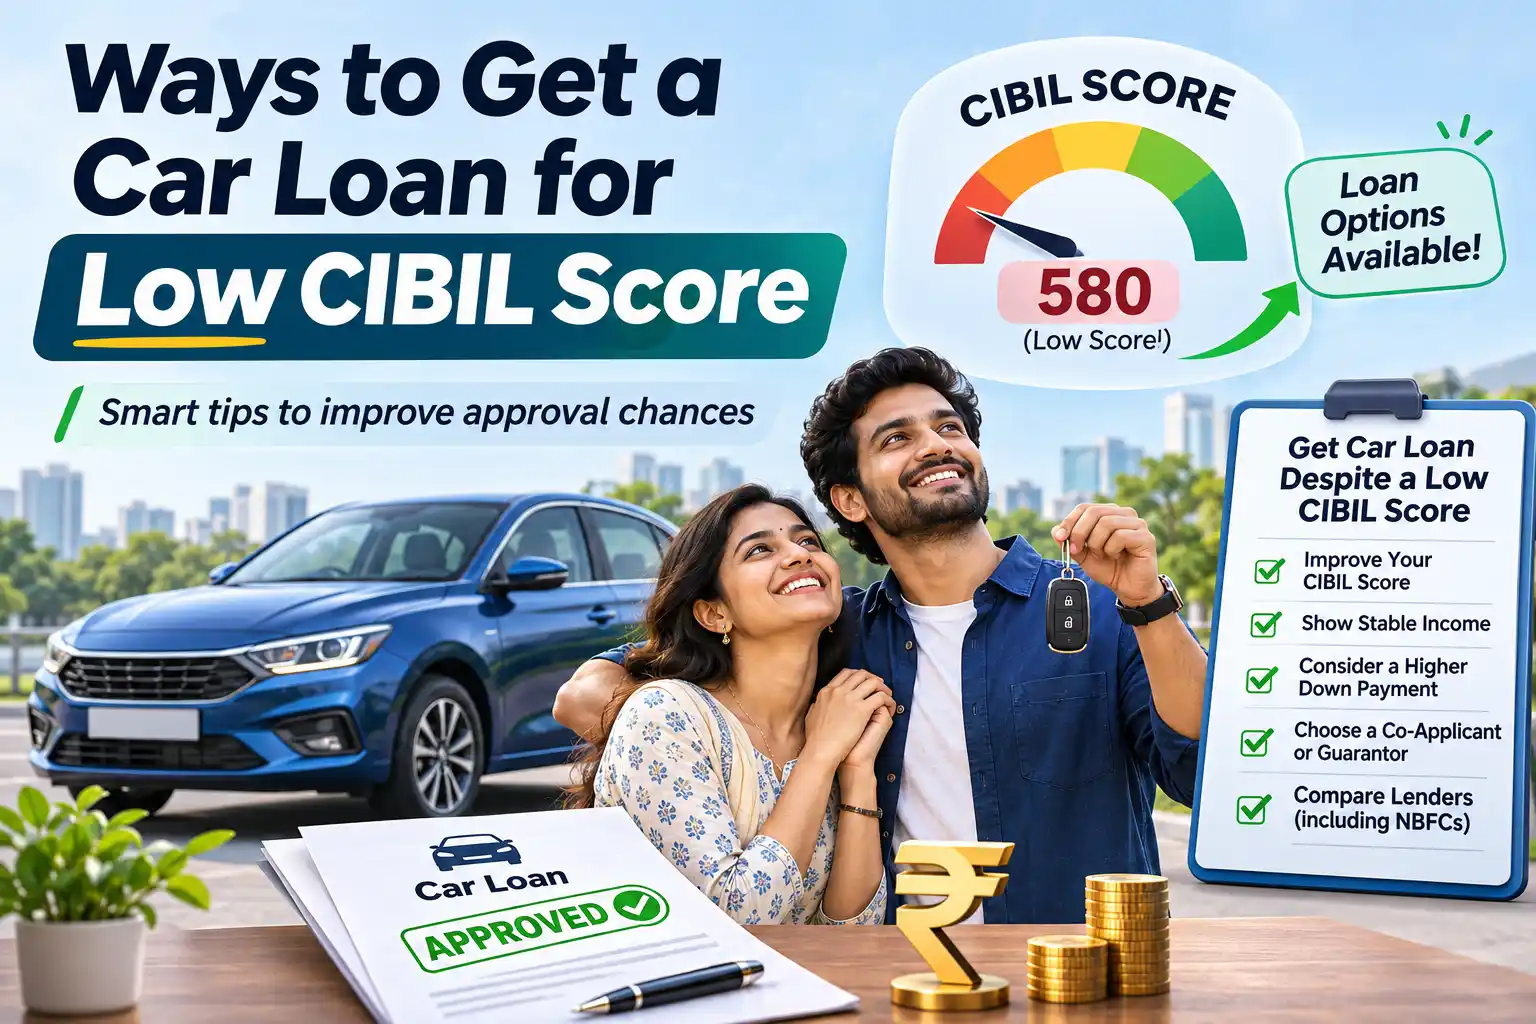
Some people face an obstacle called low income or a low CIBIL score for a car loan. However, you are not a school student worried about what grades your teacher gives you, right? You should still be able to get a car loan for low CIBIL score quite independently. This article highlights easy ways on exactly how you can do that.
Now, lenders approve thousands of car loan applications with a less-than-optimal credit score every year. The trick is to learn more about lender risk perception and find what works best for you in the car and loan market.
Ways to get a car loan for low CIBIL score
Car loans can be easier to get once you prepare
yourself from all minute perspectives that are otherwise neglected.
Check your car loan eligibility
One way to eliminate your chances of ‘collecting’ loan rejections like Pokémon cards is to begin by knowing your car loan eligibility. There are multiple tools for checking your car loan eligibility for free and without any hard inquiries. Preferably, use the tool from the bank that you are planning to get a loan from.
You can also approach an NBFC for more flexible options, but they might charge higher interest. All major banks have their own car loan eligibility check tool. This helps you evaluate your current standing and odds to find a path, fix, or method that works best for you, especially when negotiating or looking for better options. This gives you a clear idea of what to expect ahead and whether you have poor eligibility. Maybe a few fixes here and there could help you obtain a car loan for low CIBIL score.
Make a higher down payment
A lender doesn't perceive risk just for the sake of their profit or claims of the full amount, but they also check the affordability and financial capacity of the borrower. If you make a higher down payment, there are fewer requirements for interest, and there is less responsibility or a lower remaining amount due for the next couple of years. This automatically reduces the risk associated with your profile and is more profitable for you in the long run.
If you put money on the line, you are more likely to be approved for a car loan for low CIBIL score. This gives a clearer and favorable picture to lenders in terms of how you will manage the loan after disbursing it.
Check your credit report
Check your credit report to see how a car loan for low CIBIL score can be obtained with your CIBIL score and history. If you see any outstanding debts or errors like multiple accounts you don't recognize, then you can immediately take the next steps. If you see any points for improvement or errors that you can dispute, it will improve your CIBIL score if you wait a few months or more. Don’t be disheartened if you see a little less than what you would expect for the best odds; you can either improve it or still optimize your case for a car loan for low CIBIL score.
Dispute errors and clear outstanding debt
If there are duplicate accounts or repaid balances showing as open accounts, it is critical to submit error complaints. Even if they are false financial data, it will still affect lender perception, risk profile, and credit score. It is best to raise disputes at the earliest.
Outstanding debt, even if it might be a smaller amount compared to a car loan, is a very important factor that lenders check. It is an element that affects your repayment habits, because you will have to repay it along with the car loan EMIs.
The debt-to-income ratio affects your capacity and management of finances. This is why you should clear outstanding dues beforehand and think of it as a small price for getting your dream car. This leaves you with a single obligation to repay with a peaceful mind. It is also true because buying a car means added fuel and maintenance costs and even compounding interest.
Add a co-applicant
Suppose you have the right income and perfect settings to apply for your car loan for low CIBIL score, but that remains the only drawback. You can apply for a co-applicant with someone in your family or acquaintances that has a stable, disciplined credit history and a good credit score. This is definitely better than relying on your weak credit profile, even if you might actually be eligible for a loan. Yes, if you're wondering, a co-applicant with a strong CIBIL score will reduce your interest rates even if your personal score is quite low. This is because you pose as a “combo pack” to the lenders rather than an individual borrower.
Apply for a car loan for low CIBIL score at an NBFC
Non-banking financial companies are designed to assist those individuals seeking loans who were left out of the traditional banking market. They are more flexible, but they might also charge higher interest rates if your risk profile is higher than that of other applicants. If you have any of these, you might consider an NBFC like Bajaj Finserv for flexibility.
●
Irregular income
●
Low credit score
●
Shooter credit history
● Self-employment
This flexibility might also come at a price
and stand apart from standard bank loan processing. They might have different
documentation processes, higher interest rates, and stricter repayment terms
because of the higher flexibility proportion.
Choose a secured car loan
Car loans are generally secured, so they can improve your profile much better. It also reduces your interest rates, financial stress, and obligations. This approves your car loan for low CIBIL score because the lender holds the car itself as a lien. You can also check for preapproved car loan offers.
Show proof of income
Present salary slips suitable for repayment
and bank statements as documentation, which reinforces you as a stronger factor
in your eligibility. This helps the lender assess your repayment capacity in
ways other than presenting your credit score and history. Business continuity,
tax returns, and stable employment provide a promise of financial capacity for
repayment. Stable earnings are more important than a good CIBIL score,
especially for large-ticket loans like a car loan for low CIBIL score.
Compare lenders.
Comparing lenders is essential to obtain a car
loan for low CIBIL score. It is because you get an idea of what weight each
lender puts on each eligibility factor. Find which lender works out best for
you regarding interest rates, loan amount, tenure, etc.
Choose a lower-priced car or loan
In some cases, the problem might not be in the score itself but in your affordability.
Like in:
Annual income: ₹5 lakh
EMIs: ₹15,000
SUV Loan amount: ₹14 lakh
Though the score you have is good enough, you still can be declined.
By:
●
Picking up a more affordable car
●
Choosing a used car
● Taking a smaller loan amount
You would significantly increase your chances of getting the loan because of lower interest rates and more affordability proportionate to your monthly income.
What is the minimum CIBIL score for car loan
That is the most popular question among car loan applicants. And the reality is that there is no single minimum score that could secure you an auto loan. Each lending institution has its own policy.
While many of them prefer to have scores above 700, some banks and NBFCs would approve the loan even for those below this threshold, based on:
●
Income stability
●
Experience at work
●
Amount of down payment
●
Your relationship with the bank
● The credentials of the co-applicant
Thus, when asking about the minimum CIBIL score for car loan, keep in mind that the score is just one of the factors that lenders consider.
They check your entire financial profile. A
stable salary and employment at a good company is enough for a car loan for low
CIBIL score.
How to improve the credit score for a car loan for low CIBIL score
If you plan to purchase a vehicle in the
coming months, these measures will ensure that you get favorable terms for a
car loan for low CIBIL score.
Pay Your EMIs On Time
A single late payment will be seen by your credit agency as an outstanding amount.
Set:
●
Automatic payment system
●
Reminders
●
Calendars
● Auto debits
Lower Your Credit Card Usage
Most people are unaware of how much it impacts their scores.
Spending ₹95,000 per month on a 99k credit limit could show that you are in financial difficulties and affect your debt-to-income ratio.
It is recommended to keep your usage to 30% of
your limit so that you show a good repayment capacity to lenders.
Stop Making Too Many Loan Inquiries
This is something that lenders look into when
you apply for loans. When you make multiple inquiries, it gives the impression
that you are under financial pressure. Even when comparing lenders, use tools
like soft inquiries, online eligibility checkers, and
pre-qualification tools.
Pay Off All Your Outstanding Loans
Pending dues affect all of the following:
●
Your credit score
●
Your debt-to-income ratio
●
Compound interest
●
Financial capacity and discipline
Keep Old Credit Accounts
Old accounts help build credit history. A long history helps lenders learn about the behavior of borrowing over time.
Closing your oldest accounts might not always
be the best decision. It might look like you are doing a factory reset by
clearing or closing your old accounts, but the longer your credit history is,
the more credible you officially are to the lenders.
Keep a Close Eye on Your Credit Report
Checking helps you:
●
Find errors earlier
●
Identify frauds
●
Watch your score improve
● Monitor your report for any potential areas of improvement
You can't expect your score to increase
without monitoring it with complete knowledge.
Follow good credit practices
No magic trick will help you improve your CIBIL score, but a set of good practices will present you as a creditworthy person with good repayment habits.
It's a set of good habits:
●
Paying on time
●
Being responsible with cards
●
Not borrowing too much
● Keeping your inquiry requests to a minimum
Conclusion
A car loan for low CIBIL score is absolutely possible, and your credit history doesn't necessarily have to be perfect because you have many other options.
Having a high score is great, but lenders do not base their decisions on just one figure. Your income, employment status, debts, down payment, and financial behavior are also important. You can also explore NBFCs for a flexible borrowing landscape for a car loan for low CIBIl score.
FAQs
1. Is it possible to take a car loan for low CIBIL score of 600?
Yes. It is possible since some of the lenders and NBFCs might approve the loan if you have a good income stream, a co-applicant, and a large initial payment.
2. What is the lowest CIBIL score to qualify for a car loan?
The minimum CIBIL score cannot be the same for
all the lenders since most of the banks prefer the score above 700, but there
might be an exception depending on other criteria.
3. Will a higher down payment assist me in getting a car loan?
Yes. A higher down payment will decrease the long-term risk of the creditor bank, lower the sum of the loan, and increase your chances for getting the loan.
4. Do NBFCs give out car loans to those with a low credit score?
Some of the NBFCs are not very strict and accept clients even with low credit scores, but the interest rates will be quite high.
5. Is it possible to get a car loan after a default?
Yes. It is possible depending on some additional criteria, including the period of loan default, settlement of dues, your current income, etc.