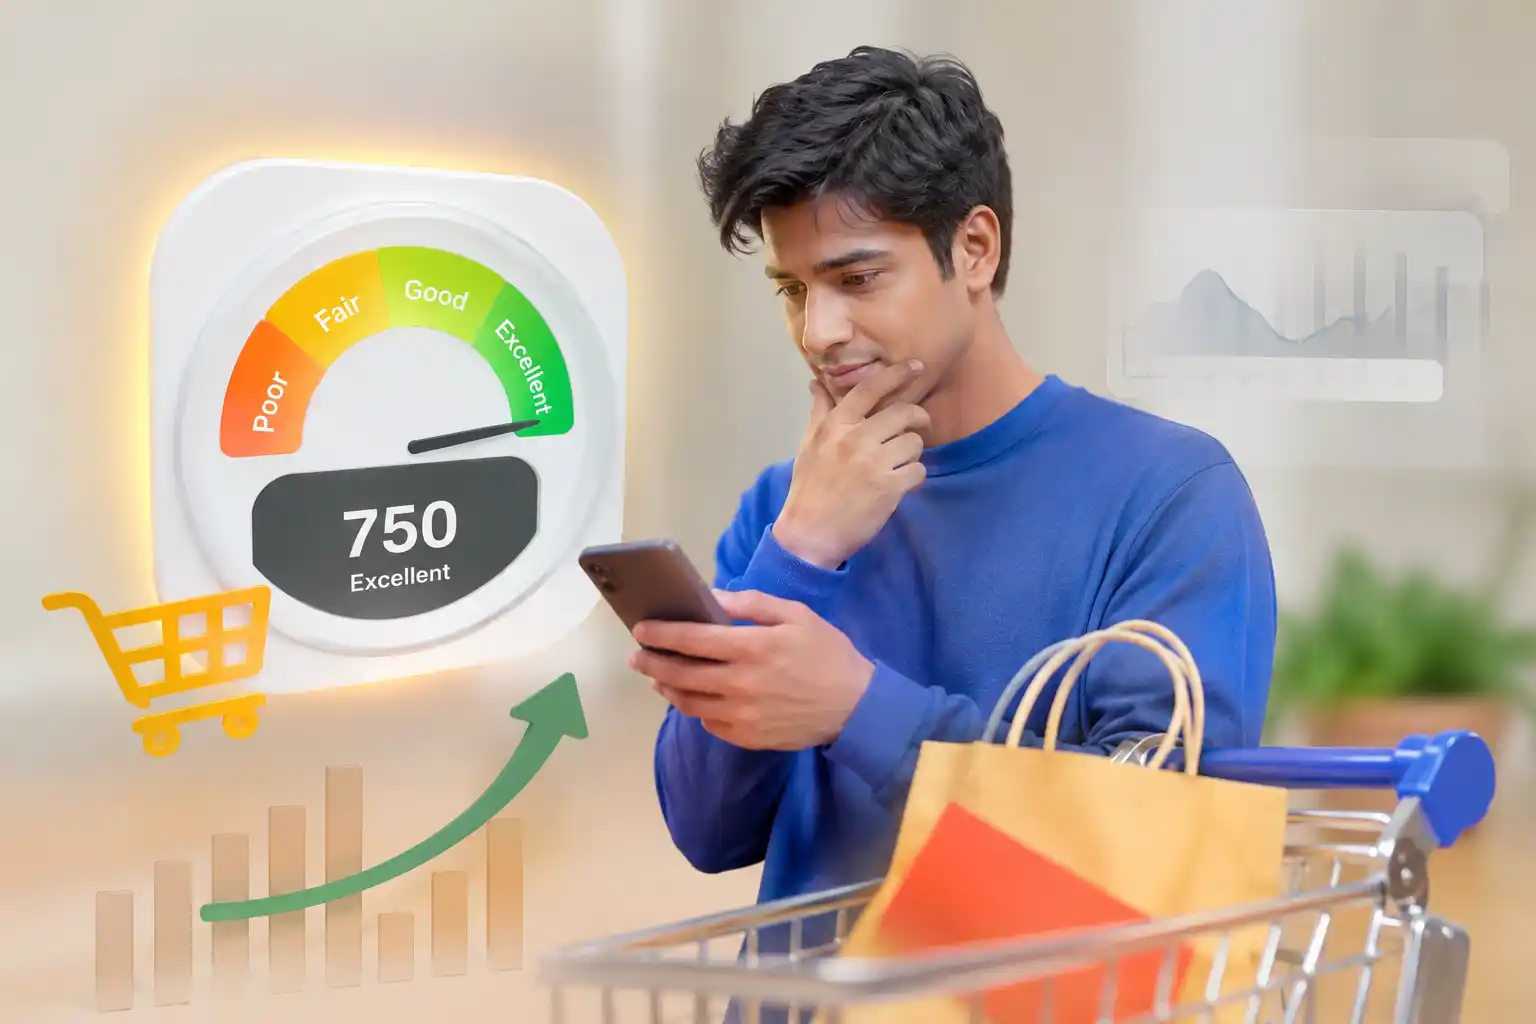
In today’s digital economy, digital enthusiasts and shopping lovers have taken over the credit market. Consumers are increasingly using EMIs, personal loans, consumer loan installments, and Buy Now Pay Later to finance purchases. Using these services may be convenient but has many financial obligations associated with it. The user gets bound to and is affected by these credit obligations for years to come.
This is where credit awareness plays a role.
Before making any financial purchase or making big life decisions, understanding your credit position and credit responsibilities is a big plus. So what is credit awareness?
Read More: Findings on credit awareness in India
Understanding Credit Awareness
Credit awareness is the comprehensive knowledge of how borrowing, repayment behavior, and financial intricacies impact an individual’s credit history and financial profile. It is the understanding of how our actions can affect and shape our financial future in the long term. It is a key trait of a credit-aware consumer.
One should be deeply aware of how lenders evaluate borrowers, interest rates, credit utilisation, credit limits, loan terms, repayment terms, and credit scoring algorithms.
Financial experts have stated that credit-aware consumers manage credit with discipline. Not only do they enjoy rewards, a good credit score, and convenience, but they also pay back the full amount every single month. Because they don't pay interest, any rewards or offers turn into profit. Credit is not a ringing alarm for them.
Credit awareness also allows consumers to recognize predatory lending practices, additional fees, and poor borrowing terms.
In a practical sense, credit awareness is about the ability to answer some questions before shopping:
● Am
I able to finance the product/service?
● Does
it make me more indebted?
● What
impact will it have on my credit utilization?
● Will
I be able to cover future payments easily?
● Is it wise to finance this purchase?
This knowledge will allow consumers to make better decisions according to their financial priorities.
The concept of credit awareness becomes
particularly important in today’s age of numerous online lenders, quick loans,
and other convenient ways of financing purchases. While easy access to credit
is good, it does not bring any benefits without proper knowledge of the
consumer’s responsibilities.
Understanding credit score
Credit scores help lenders estimate how likely a borrower is to pay on time. Higher credit scores help consumers qualify for better interest rates and loan terms.
Credit scores are not static. Some changes are temporary, and they have the capacity to be improved. Few perks of a good credit score:
● easier
loan approvals
● lower
interest rates
● better
credit card offers
● greater
financial flexibility
● higher credit limits
How to Increase Credit Awareness
Continuous learning, active participation,
and responsible credit management can increase one’s credit awareness.
1. Monitor your credit report
Following best practices and constantly
checking your credit report periodically makes you aware of the consequences
and results of your own financial decisions. It helps filter out or rectify
incorrect information or remove critical delinquencies. You can analyse how
different activities shape your credit score, both positively and negatively.
2. Understand basic credit terminology
It might sound insignificant because it’s “basic,” but the truth is it depends on a person's experience, understanding level, and use of these credit terms.
● Annual
Percentage Rate (APR)
● Credit
limit
● Minimum
payment
● Credit
utilisation
● Soft
inquiry
● Hard
inquiry
● Secured and unsecured credit
3. Monitor spending habits
Tracking expenses provides valuable insights
into borrowing behavior and financial discipline. Consumers who monitor
spending are most likely to recognise unhealthy credit patterns before crashing
into a debt trap or high interest.
4.
Use Educational Resources
Government agencies, financial institutions,
and financial literacy programs offer online resources to educate consumers
about finances and credit management. They let the reader dig deeper into the
functions of the credit system for healthy financial decision-making and a good
credit score.
5. Read loan and credit agreements carefully
Many consumers focus only on monthly payment
amounts without examining other terms such as interest rates, processing fees,
and penalties. Reading agreements carefully improves credit awareness and
reduces the risk of unaffordable financial traps.
6. Follow Expert Advice
Subscribe to the newsletters and follow
financial experts on LinkedIn who constantly talk and post about financial
literacy, budgeting, and debt management. Small changes in behavior can create
a larger picture.
7. Create a Financial Plan
A structured financial plan helps consumers
align purchases with their income, long-term goals, and current obligations. It
creates a sense of responsibility and controls impulse spending.
8.
Understand Credit Reporting
Systems
Credit reporting systems work based on past
repayment and financial behavior. Credit reporting can improve access to credit
products by helping users build and improve a documented financial history for
loans.
Factors that affect credit
score
There are several factors that affect the
calculation of credit scores. Although there are Minor differences in
algorithms, most scoring models have similar factors concerning borrowing
behavior. This creates a comprehensive picture for those who want to inculcate
credit awareness and a good credit score.
1. Payment History
Payment history makes up 35% of the credit score. Lenders require proof of ability and willingness to repay debts and meet other obligations on time.
Late payments and outstanding debt affect the
credit score adversely and remain reflected on the credit report for a long
period. According to the consumer finance advisory, paying bills on time has
one of the biggest effects on maintaining a good credit score.
2. Credit Utilization Ratio
Credit utilization ratio refers to the proportion of available credit limit used by the consumer.
For instance:
Credit Limit: ₹100,000
Outstanding Balance: ₹30,000
Credit Utilization: 30%
Generally, it is advised to keep the credit
utilization ratio below 30%, as higher credit utilization affects the score
adversely. It accounts for 30% of your credit score.
3. Length of Credit History
The length of credit history increases the amount of information provided to the lenders. It is the full record of your financial activity, transactions, and repayments. It is also known as credit age, which is the average age of all accounts and the age of your oldest and newest accounts.
Credit age shows valuable experience of
credit management. Consumers with thin credit histories have difficulty
obtaining credit since lenders do not have adequate information.
4.
Credit Mix
Having diverse credit accounts shows that you
have the financial agility to manage different types of debts instead of just
one. Example: credit cards, personal loans, home loans, auto loans, and
education loans.
5. Recent credit applications and inquiries
Making too many applications during a short period of time shows financial distress. Too many hard inquiries can lower your credit score on a cumulative basis. Therefore, maintain a gap between applications and only apply during times of need.
Benefits of credit awareness
1.
Better financial
decision-making
Consumers who understand finances better are
likely to make better and informed financial decisions. The smallest of
informed actions can contribute to a different larger picture. They compare
terms, analyse costs, and make proactive decisions, which goes beyond just EMI
reminders.
2.
Improved credit scores
Awareness of credit factors encourages
responsible financial behavior. Users show greater discipline towards important
credit score factors and improve their credit score, which leads to a better
financial future.
3.
Lower borrowing costs
Good credit scores have lower interest rates.
Even small differences in long-term loans can result in compounding and
cumulative charges, resulting in a debt and interest trap.
4.
Better access to credit and
financial products
A person never knows when they need emergency assistance. They could never be prepared enough for big life-changing decisions like home loans and car loans. Staying ahead of these timelines comes from a credit-aware person who understands the importance of future financial products better than others. You get faster approvals and favourable loan terms.
Not just for loans, but a credit-aware
professional manages their finances at a higher level than others. This is why
they enjoy rewards, perks, a good credit score, and premium credit card offers.
4. Stronger negotiating
power
A credit-aware person has higher negotiating power and the opportunity to compare lender options or loan offers. Creditworthy consumers often get favorable offers from lending institutions like:
● high
credit limits
● low
interest rates
● fewer
fees
● Good
behavior grace
● fewer
additional charges or processing fees
● better
repayment plans.
5. Fraud detection and prevention
Consistent checking of credit reports
provides consumers with early identification of any potential fraud or identity
theft, reducing the chances of financial loss.
6.
Helping Meet Major Financial
Objectives
Some of the major financial goals that can be helped through credit awareness include:
● Purchasing
property
● Purchasing
cars
● Starting
up a business
● Attending
college
● Wealth creation
Strong credit enhances the ease of meeting
these financial objectives.
7. Less Financial Stress
Unexpected challenges or interest traps
associated with debt often cause financial and emotional stress. Financially
savvy consumers are well equipped to deal with their debts without financial
surprises.
8. Financial Inclusion
Research on global finance emphasizes the role played by the credit reporting system in enabling consumers to create a record of their financial activity. This opens a world of opportunities and financial products.
Conclusion
Credit awareness is an essential component of the modern financial world. The complexities of credit management and finance are constantly evolving; it is essential for modern people to keep up with the times.
Credit-aware people are one step ahead of
people who only learn to manage the basics. Credit awareness also helps a
person manage their impulse shopping behavior. It is more than just a numerical
representation—it builds long-term financial inclusion, a foundation for
financial success and confidence.
FAQs
1. Do credit report checks lower credit scores?
A soft credit check, like a personal credit
report check in routine monitoring, does not affect your credit score and is
not visible to anyone but you.
2. What should my credit utilization ratio be?
Most financial advisers suggest a credit
utilization of below 30 percent, which is ideal.
3. What are good credit score practices?
Some ways that one can have a good credit
score include paying bills on time, having a low credit utilization ratio, not
making too many credit inquiries, checking credit reports, and debt management.
4. Does my credit score influence the approval of my loans?
Yes, lenders take credit scores into
consideration while processing loans. It affects the terms, negotiations,
interest rate, and much more.
5. How does credit knowledge help me plan for my finances?
Credit knowledge allows borrowers to make
informed borrowing decisions, reduce financing costs, increase financial
security, and reach financial objectives.