Buy Now Pay Later is a boon for tech-savvy credit seekers, millennials, and Generation Z in the age of increasing online shopping. It is used to fill the gap for those who can't get credit. It is used as a loan for those who can't pay an upfront amount immediately but want to pay back in equated monthly installments.
Young
professionals, early-career youngsters, and college students find it
convenient. For modern and curious millennials, such a digital-first, one-tap
mobile setup is much more preferable than heavy paperwork for every single
loan. 93% of Indians are devoid of traditional
credit. Therefore, it is a suitable option for such people who are actively
adopting this credit mechanism.
What is Buy Now Pay Later (BNPL)?
Buy Now Pay Later is a short-term loan that helps a person pay back for shopping in monthly EMIs. The difference between a credit card and BNPL is that BNPL is a short-term loan for an individual purchase, while a credit card is a revolving line of credit with a specific credit limit.
For some plans, the plus is you don't pay interest for timely balance payments. Otherwise, you pay a late fee. In fact, most providers and lenders make money by charging a merchant fee instead. Way to go for active money savers. This is actually applicable to standard “Pay in 4” plans. If you make a larger purchase that spans over 6 months to 2 years, the lender might charge an annual interest rate. Most Buy Now Pay Later (BNPL) schemes require a 25% down payment at the time of purchase.
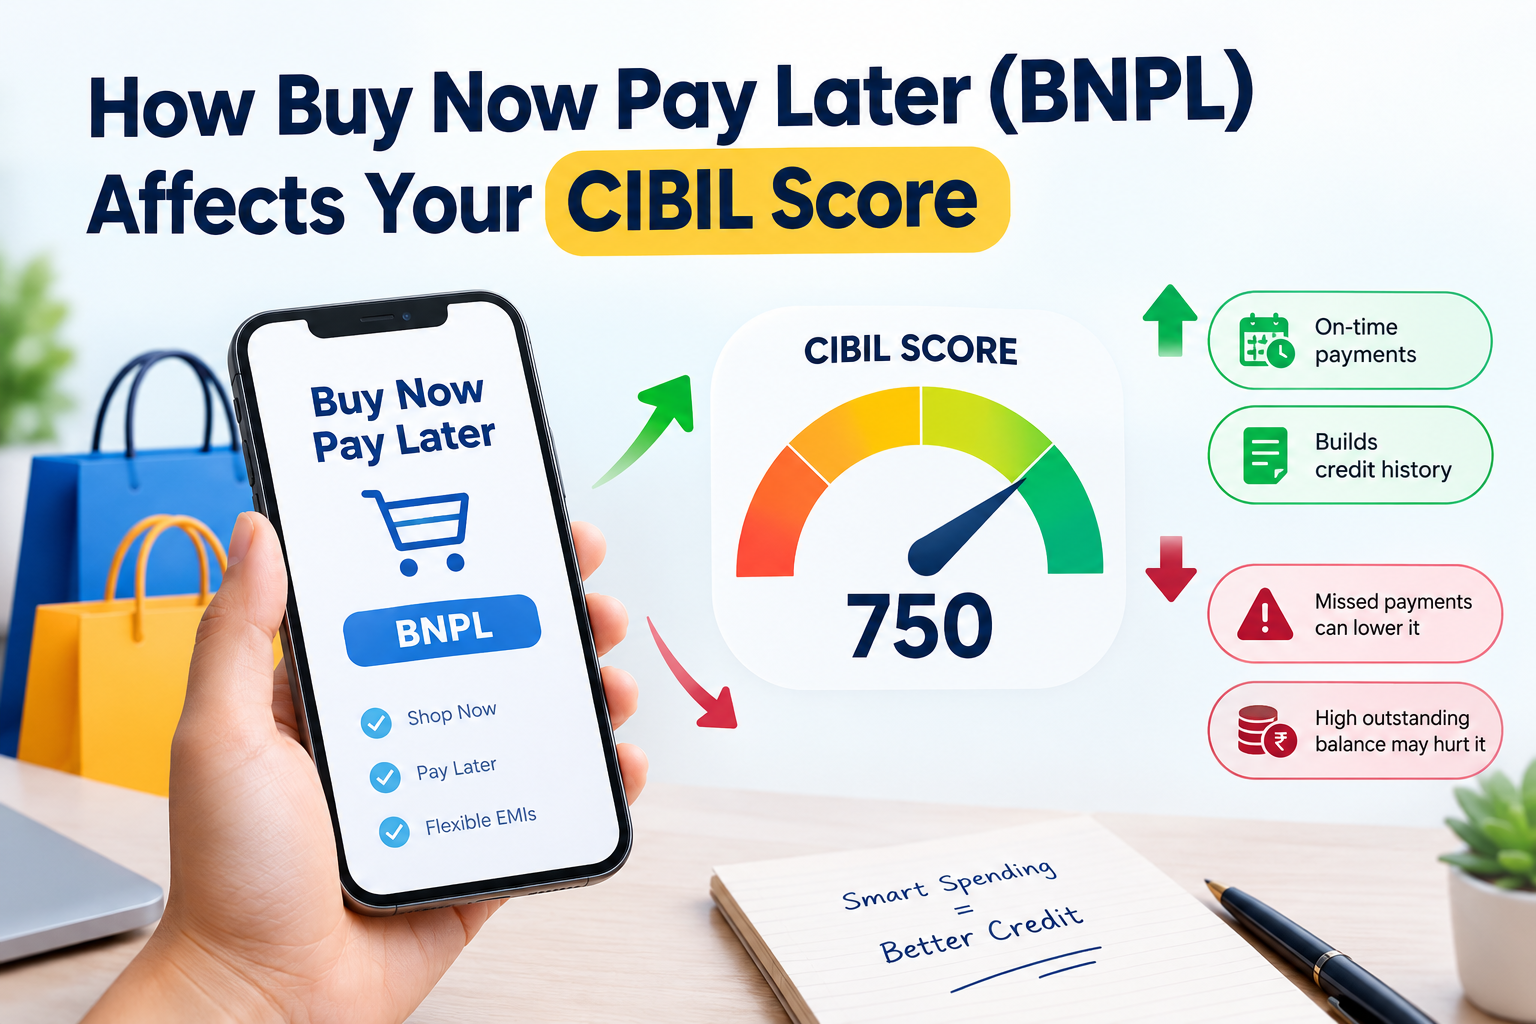
Buy Now Pay Later and CIBIL Score
Check if your provider reports payments to the credit bureaus. If yes, it is important to make sure that you make timely payments so that it doesn't affect your CIBIL score negatively.
BNPL can be convenient and help with cash flow management, savings, and credit for an interest-free period, but it also significantly affects your credit profile. Missed payments can stay in your credit report and cause you a late fee. It doesn't matter if the lender's policy reports missed payments to the bureaus. Any defaults are quickly escalated to the collections agency that sends records to credit bureaus. Nevertheless, this affects your future borrowing eligibility.
When
you sign up for Buy Now Pay Later apps, the provider may perform a hard inquiry
to assess your creditworthiness. While one inquiry generally has a limited
impact, several hard inquiries can communicate a dependence on credit.
Positive impact
● BNPL can be used easily by first-time borrowers.
● It creates a track record of
timely repayments.
● Shows a history of financial
discipline.
● Most BNPL and small loan
approvers use a soft check on the borrower instead of triggering a hard inquiry
that lowers your credit score.
● Healthier overall credit mix.
● Requires no interest
Negative Impact
● Missed or late payments
● Shorter tenures can't be used
to build a long history.
● Defaults are sent to
collections
● Some providers may still run
a hard inquiry
● Opening BNPL accounts can spike
your credit utilization since it doesn't have a credit limit. Lenders can still
view this.
● Building interest-free
history can be a golden opportunity, which is missed if the lender doesn't
report to CICs.
Some Buy Now, Pay Later Apps in India
In India's fast-evolving digital lending ecosystem, Buy Now Pay Later apps and platforms have transformed how consumers make purchases. Leading players include Simpl, LazyPay, Amazon Pay Later, Flipkart Pay Later, Slice, and Uni Card. Additionally, major banking institutions offer BNPL features integrated directly into net banking and credit card apps, such as HDFC FlexiPay and ICICI PayLater.
From a credit perspective, BNPL services function as short-term, micro-personal loans or revolving credit lines. Once you sign up for or use these services, these companies, which are NBFCs or banks, will usually file a credit card against you in your true identity at credit agencies such as CIBIL and Experian.
Although
these portals give you immediate checkout and zero interest periods, using
these sites will affect your credit report. All payments made by you, any
credit increase, or even small inquiries made by you from different BNPL
applications will be recorded by credit bureaus. Your credit score will suffer
if you have outstanding dues on different BNPL applications.
The Right Way to Use BNPL
BNPL
might be a convenient tool, but some people still tend to make mistakes while
using it. To avoid these, follow best practices for using BNPL. Its use should
be controlled and restricted, rather than using it as free money. They need to
understand that each purchase must be paid off at some point in time.
Never Apply for BNPL for Impulse Purchases
Think of it: when choosing a BNPL service, will you still be able to buy something in the absence of this payment option? If your answer is negative, you may make an impulsive purchase.
The best ways to apply for BNPL:
● For electronics that are
needed for working or studying.
● In case of emergencies.
● For planned purchases for
household needs.
● For travel expenses.
● For buying clothes and other stuff on sale.
Do
not finance anything that goes beyond your budget.
Always pay all the bills before the deadline.
Payment history is among the most influential factors for your CIBIL score. Make sure that you are always reminded about the deadlines, you pay automatically, and you have enough money to pay.
Users
often miss small BNPL payments and get bad marks on their CIBIL score just
because of it.
Remember All Active Deals
Users often have multiple deals open on their various BNPL applications. Keeping a simple list including:
● Amount to be paid
● Deadline
● Remaining balance
● Monthly installment amount
will
help avoid late payments. Essentially, avoid using multiple accounts unless you
pay the previous one.
Make Sure You Know All the Terms of Service
Not all BNPL services operate the same way. Some provide a period during which you can make payments without interest, while others charge interest, convenience fees, processing fees, and/or late fees.
Make sure that before starting any purchase, you know:
● Terms of repayment
● Late fee terms
● Interest rates charged
● Policy about reporting credit
information
● Automatic debit terms
● Stick to no-interest plans. What's the point of using BNPL when you still pay interest like credit cards?
Do Not Use BNPL to Make Everyday Purchases
Buying everyday items like groceries, food deliveries, and streaming services with BNPL may mean that your budget is under stress. Such behavior leads to a vicious cycle where future income is spent repaying previous expenditures.
The general rule is that monthly payments on BNPL deals should not be more than you can pay without straining your budget to pay rent, utilities, savings, and investments.
Remain Financially Disciplined
BNPL
use should be just one element of your credit management plan. You need to
continue using credit cards responsibly, paying loans on time, and making important
savings. Responsible use and management of all financial products is more
important than relying on them. If possible, turn on autopay and watch out for
late fees.
Buy Now Pay Later Mistakes
Credit
score problems for many consumers do not occur as a direct consequence of BNPL
but as a consequence of their own faulty use.
BNPL is used for buying on a whim
Discounts, promotions, and easy approvals may lead to excessive spending because, as no immediate payment is necessary, people tend to undervalue the expenses.
Frequent
small purchases can turn into substantial repayment amounts.
Delaying Payments
Delaying payments is still the worst BNPL mistake you can make. The overdue payment might result in:
● Charges.
● Collections.
● Negative reporting to credit
bureaus.
● Lower creditworthiness.
Even
though it is a relatively small amount, the consequences of this mistake may
turn out to be severe.
Overlooking Total Balance
Many people tend to consider monthly payments instead of the total BNPL balance. This approach may give you an illusion of being more affordable than in reality.
It is always better to look at the full balance before applying for any new BNPL loan. This is because it is still visible to lenders; nevertheless, they view it as total debt due rather than separate balances. This leaves an impact on future borrowing opportunities.
Before
applying for another BNPL loan, it is recommended to check how much you
currently owe.
Stacking BNPL Accounts
Each new application triggers a credit check. Frequent opening of new BNPL accounts shows that the person is heavily dependent on credit.
Lenders
analyzing your account may get worried seeing a number of new accounts being
opened recently. On top of that, multiple Buy Now Later apps for shopping,
groceries, and clothes can make the user lose track of total expenses and
balances.
Not Being Familiar with Penalty Schemes
Various buy now, pay later apps have different rules about how much they charge for a late payment, interest, and collections.
Most
users find out about all those costs when failing to make payments. It is
important to familiarize yourself with them beforehand.
Exceeding Repayment Capabilities
The biggest mistake is to borrow more money than you are able to pay. Credit should be just an addition to financial planning.
It
is better to make sure that future repayments will be easy to manage.
Automatically assuming that BNPL doesn't affect credit scores
Some users incorrectly believe that BNPL is invisible to lenders. BNPL is subject to reporting on lenders' policies and practices. Even if it is not reported, missed payments and delinquencies can still appear on your credit profile.
Missing Due Dates
Neglecting the importance of BNPL or viewing them as ‘small ticket purchases’ can lead to missed due dates.
What happens if you use multiple BNPL apps
With the emergence of so many Buy Now Pay Later apps in India, it is very convenient to open several accounts. But while having accounts on several platforms is not necessarily risky, it brings about various financial dangers.
Higher Credit Exposure
Every BNPL service constitutes borrowing. The more platforms you use at the same time, the greater your debt will be.
For
instance, making a small purchase on five different platforms seems like
nothing until you sum up these purchases and realize that the total can pose
great stress on your budget.
Greater Possibility of Late Payment
Each platform tends to operate in its own cycle of billings and payments. It becomes increasingly complicated to manage all these deadlines.
The
more deadlines you are responsible for, the higher your chances of overlooking
one of them.
Decreased Eligibility for Loans
All outstanding debts are taken into account while evaluating loans.
If you have a number of Buy Now Pay Later schemes on your credit report, lenders will assume that your existing debts are already high.
It may influence:
● The approval of personal
loans.
● The eligibility for home
loans.
● The issuance of credit cards.
● The application for vehicle
loans.
● The amount of loans issued.
The Issue of Debt Fragmentation
An underappreciated issue is debt fragmentation. Instead of handling one payment schedule, the borrower will be responsible for paying several apps.
Such
fragmentation brings problems, as it confuses people, adds stress, and
complicates budgeting.
Cash Flow Difficulties
The problem here is that many BNPL users arrange purchases in advance. With the installment dates overlapping, it leads to problems with cash flow.
The person who can manage one or two BNPL loans without any difficulties will find it hard to handle six or seven payment schedules at once.
Conclusion
Buy Now Pay Later Services have transformed consumer spending in India by providing convenient access to short-term credit. When used responsibly, Buy Now Pay Later apps can help build credit history, improve repayment records, and support financial flexibility. However, misuse can lead to missed payments, increased debt, lower CIBIL scores, and challenges obtaining future credit.
Understanding the key to responsible BNPL usage is simple: borrow only what you can repay, avoid multiple accounts, and use it as a financial tool rather than extra income. The exciting offers and design of the Buy Now Pay Later schemes can catch you off guard, but it is important to not lose track. Many users tend to overuse the facilities when they should be paying discretion.
FAQs
1. Does Buy Now Pay Later Affect CIBIL Score in India?
Yes.
It can. Even if it is not reported by lenders to credit bureaus, it can still
be reported by collection agencies if you miss payments. If it is reported by
lenders, then it can contribute to valuable interest-free credit history,
especially for first-time borrowers.
2. What happens if I miss a payment on my BNPL account?
You may face late charges, collections, and a negative entry on your CIBIL report, leaving a negative impact.
3. Are multiple BNPL apps bad for my credit history?
It
is advised against using multiple BNPL accounts at once because borrowers can
lose sight of how much the small balances can add up to as a cumulative credit
balance. It can make it difficult to pay back and leave a bad impression on
lenders.
4. Can first-time borrowers use Buy Now Pay Later?
Yes,
for those with limited credit history, BNPL is an effective way to establish
credit history and a borrowing history.
5. Are Buy Now Pay Later options free?
No, not all Buy Now Pay Later options are free. It is important to familiarise yourself with the terms and conditions. Only the standard quarterly installments are interest-free. Larger ticket loans and longer tenure loans will still charge interest. There might even be some processing or other fees involved.