Many
people have the notion that checking their personal credit score will reduce
their credit score. The truth is, checking your own credit score is a healthy
habit that builds your financial and credit management skills, not a negative
factor in your credit history. It is called a soft enquiry.
Does loan inquiry affect credit score? You can answer this question by differentiating between soft and hard inquiries. A pre-approved offer is not a hard pull; it is a soft enquiry on your credit profile. However, disbursing the loan amount for the pre-approved offer becomes a hard enquiry. So what is a hard enquiry? How is it different from a soft enquiry?
What is a hard loan inquiry?
A hard enquiry is when a bank or lender checks your credit report and credit history when you apply for a loan. This is part of the formal loan application processing.
Does loan inquiry affect credit score?
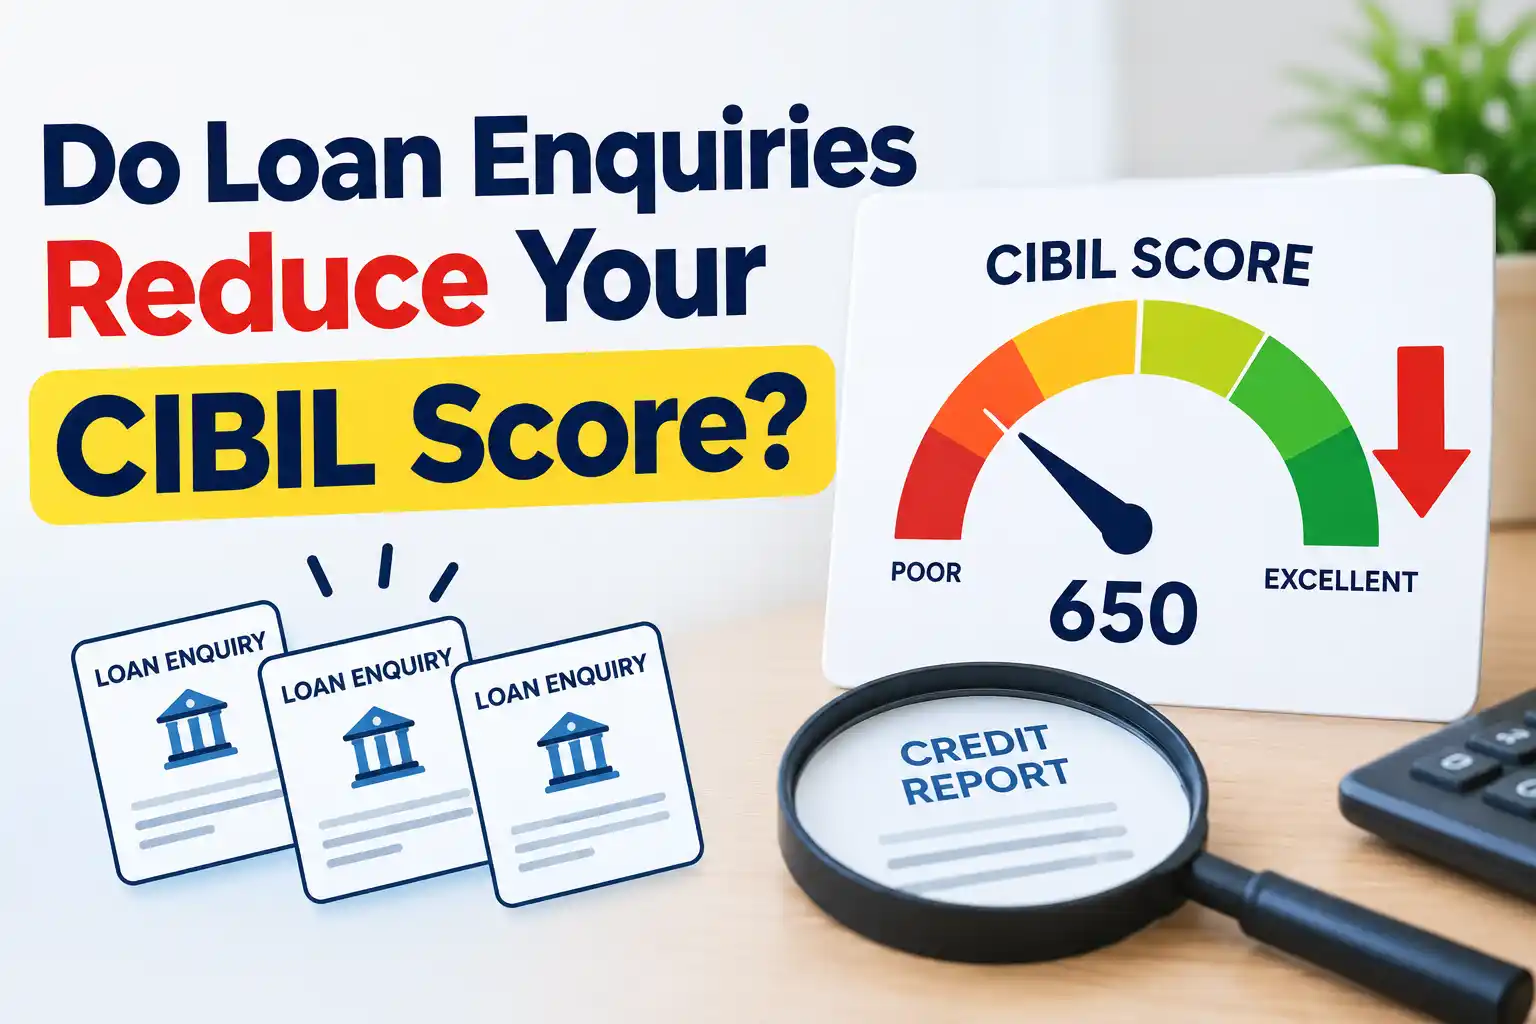
A single hard enquiry can drop your credit score by 5 to 10 points. If you make multiple hard applications, this shows desperation for credit and leads to a cumulative point drop of up to 50-60 points.
Therefore, it is advised to make applications one at a time. Wait for the final decision or use soft enquiry tools. There is also a healthy strategy called rate shopping, but this only applies to loan applications, not credit card applications, which are revolving credit. We’ll talk about this later.
● A hard enquiry is visible to
all lenders simultaneously reviewing your application.
● Every legitimate loan inquiry
stays on your credit report for 24 months.
● The negative impact is likely
to decrease in the year following the date of application.
● Every hard enquiry is visible on the “enquiries” section of your credit report.
A hard enquiry helps a lender analyse and evaluate your credit repayment habits and make a final decision towards your loan application:
- Whether you are eligible for the
loan
- Whether you meet the
requirements
- How much loan amount they should
disburse to you
- What should be the interest rate
and tenure
- What is the default risk
associated with your profile
- Debt-to-income ratio
- Status of employment or
self-employment
- Collateral and loan-to-value
ratio for secured loans
- The existing debt that you will
be paying alongside the loan you have applied for
- Whether you are financially
capable of repaying
- Whether you can make timely payments, etc.
Read
more: Hard Inquiry vs Soft Inquiry
What is a soft loan inquiry?
A
soft enquiry (also known as a soft pull) occurs when your lender, the platform,
the background check, or even you personally look at your credit report without
doing an official credit application. This is done for purposes such as
information gathering, pre-screening, or identity verification.
Does loan inquiry affect credit score?
A soft enquiry carries absolutely no effect whatsoever on your credit score—it won’t harm your score in any way, regardless of how many times it happens.
As a result, you can check your own score as often as possible with no repercussions. Soft inquiries allow you to monitor your profile health, check the accuracy of your credit reports, and compare pre-approved loan options securely before making an actual application.
● Soft enquiries remain
completely invisible to third parties; soft pulls can be viewed by yourself
alone when you check your own credit report.
● Soft enquiries are logged in
your personal bureau file to ensure that there is a transparent record of those
who accessed your information.
● Since no score drop occurs,
there will be no negative impacts, which will have to recover from.
● Every soft loan inquiry will be classified as a separate entry within the internal access or soft audit log of your personal credit report, and it is considered a healthy credit habit rather than a credit-hungry flag.
A
soft loan enquiry assists the lender/institution/platform to check the credit
status of your background for these reasons without affecting your score:
Self-Assessment
For
checking your credit score and report via the official applications or bank
portals to assess your financial status.
Pre-Authorized Credit Offerings
For
allowing banks or financial institutions to scan your credentials to see if you
fit the criteria for their pre-authorized credit card/personal loans or credit
limit increase.
Employment Verification
For
assessing your financial reliability and debt history for pre-employment
assessment (commonly done in banks, finance, and security fields).
Rent Check
To allow your landlord/property management
agencies to assess your financial status before renting a property from you.
Existing Lender Account Review
To
allow your existing lender to carry out periodic checks on your account status
to manage credit risk.
Verification Purpose
Assist
insurance companies, utility providers, or identity verification agencies in
verifying your identity and history of addresses.
Insurance Underwriting
Assists
insurance companies in analyzing their risk profiles (where credit histories
impact insurance premiums).
Debt Counseling/Portfolio Management
Assists
financial advisors or credit repair services in assessing your outstanding
debts to come up with a payment plan.
Pre-screening for Promotional Marketing
Enables
financial service providers to remove any ineligible profiles from receiving
loan or credit card offers.
Internal Credit Bureaus' Auditing
Used
by credit bureaus for internal system maintenance and upgrades.
Difference between credit and loan enquiries
Many borrowers assume that all enquiries on a credit report are the same, but there is an important distinction. A credit enquiry occurs when a lender reviews a person’s credit history for a credit card application. A loan inquiry is the hard pull a lender performs to check a person’s repayment ability towards a home loan, auto loan, personal loan, etc.
There is also a difference in the impact of hard enquiries. In the case of a loan inquiry, you can specify your timeframe to limit all hard enquiries so that they are counted as one window of rate shopping. On the other hand, that doesn't apply to credit card applications because they are a type of revolving credit.
Is there a solution to “Does loan inquiry affect credit score?”
What is rate shopping or deduplication?
Rate shopping is defined as a process in which an individual compares loan offers from various lenders to choose the best fit. Borrowers reach out to various banks and financial organizations to compare interest rates, repayment terms, processing fees, and features of the offered loan. Obviously, such a situation will lead to multiple loan inquiries within a short span of time.
To protect borrowers from being negatively affected while looking for the best loan deal, the credit reporting agencies apply such measures as deduplication for a loan inquiry.
This means that multiple inquiries of the same loan type that are done within a certain time frame may be considered as one loan inquiry. The idea is that a person tries to get the best possible loan and not just to apply for multiple credits. In India, this time frame is 14 to 30 days, and up to 45 days for some home and mortgage loans. This is a protection method as an answer to “Does loan inquiry affect credit score?”
This particular measure applies mostly to home loans, education loans, and auto loans in which a person looks for the best deal before they choose a loan. This is only in respect to a loan inquiry and not a credit card inquiry. Do your research for appropriate and eligible options.
Although there may be some variations in the policies of each credit scoring model, this measure helps minimize the effect of rate shopping on the credit score. Nevertheless, people should try to avoid applying for many loans over an extended period of time.
● Remember to stick to one loan
type. Avoid credit cards or other applications.
● The window of rate shopping
is 14 to 30 days, and up to 45 days for some home and mortgage loans.
● Finish your work in two weeks to limit loan enquiries.
Does loan inquiry affect credit score: Impact
A single loan enquiry generally has a low impact on a borrower’s credit score. A person with a high CIBIL score, like 750, will experience a lower point drop, like 2 to 5 points. It is seen as a low-risk routine check. For low CIBIL scores like 680, it is seen as financial dependency, and creditors find it hard to balance the risk out with any pre-existing good history or factors. This difference comes from the irregularities in the buffer provided by the stability levels in each score.
Does loan inquiry affect credit score?
One loan enquiry has very little effect on the borrower's CIBIL score. The credit bureaus know that people will look for finance and compare loan offerings at times. Issues start occurring when there are many hard enquiries in a very short period of time.
Many enquiries may give the impression to the lenders that a person is in desperate need of credit or in some kind of financial distress. As a result, the credit scoring system may take it as a risky move on the part of the borrower. Even though a decrease in the score is not very severe due to a single enquiry, repeated attempts will eventually reduce the score and cause apprehension among future lenders.
To further explain, “Does loan inquiry affect credit score?” It is more likely that the effect on the score is greater in the cases of unsecured credit offerings such as personal loans and credit cards. This is because the credit products carry a greater risk of default, and therefore many attempts will bring additional attention from the lender's side. Besides, when going through the credit report, a lender may think that there are many rejections of the application from other financial institutions.
When a person wants to get a large loan, maintaining a low number of hard enquiries on your credit profile reflects responsible borrowing and improved approval prospects.
How to manage the impact of loan inquiry
Although hard inquiries are an inevitable feature of the loan application process, borrowers can take informed and healthy steps to manage the effects of a loan inquiry. Comparing lender and loan options is a good practice, and it should not weigh heavily on your credit profile. This is why many healthy practices enable and empower a borrower to research their options before applying. This is another aspect of "Does loan inquiry affect credit score?”
- Research and be informed of your options before applying. Check the interest rates, eligibility requirements, and loan amounts for each lender or bank. This improves your odds and reduces the number of unsuccessful or unfavorable applications. After this, you can use the rate shopping strategy if you are eligible for it.
- EMI calculators, eligibility tools, and pre-qualification tests would enable narrowing the list of potential lenders without conducting additional hard inquiries. Applying for multiple credit cards or personal loans at once can be avoided unless necessary. The application process needs to be timed properly in order to give the credit profile enough time to recover from previously conducted inquiries.
- A good credit score can help offset the negative effect of loan inquiries as well. The lenders consider the entire credit profile of the borrower, not only the number of enquiries conducted.
An individual who demonstrates regularity in payments and a responsible approach towards dealing with debts has more chances to receive a positive decision despite a couple of recently conducted inquiries.
- Finally, it is recommended to check one's credit report periodically in order to detect any mistakes or unauthorized inquiries. Eliminating the errors will help maintain the credit profile in an accurate state. Proper management of loan inquiry can reduce their negative effect on the credit score significantly.
FAQs
1. Does my hard inquiry show up in the credit report after 30
days?
RBI has mandated fixed dates instead of random weekly or monthly updates. The said dates are the 9th, 16th, 23rd, and 30th/31st monthly dates.
2. What are EMI calculators and pre-qualification checks?
Before applying for a loan, many borrowers use EMI calculators and pre-qualification tools to avoid hard pulls. An EMI calculator is an online tool that helps estimate the monthly repayment amount based on your loan amount, tenure, interest rate, etc., based on a lender’s structure.
Pre-qualification
or loan eligibility checks are preliminary assessments conducted by lenders to
determine whether a borrower qualifies for a loan. It is done in the form of a
soft inquiry using the information provided by you to the lender. This doesn't
guarantee final loan approval.
3. Do secured loans trigger hard inquiries?
Yes,
even though secured loans are backed by collateral, the lender still performs a
hard pull on your credit report to check your history, score, and collateral.