We have heard about the ambiguity in credit reporting and sending consumer credit information to bureaus. From lenders to banks, NBFCs, and credit card issuers, there is always a need to check if the lender or data furnisher is sending your data to credit bureaus at all. We are also aware that a lender might not send your information to every bureau. One lender might send data to one bureau, and another might send it to another bureau.
However, is this ambiguity consistent in banks as well? Which credit bureau do they consistently use or prefer? Which credit score do banks use in India primarily when making lending decisions?
This reporting or sending of information is highly voluntary rather than strictly mandated for data furnishers or creditors. The RBI mandates all lenders to report data and be members of all four major bureaus in India. However, every bank or lender might choose who to report to based on their internal policy or other factors. Pulling reports from all four is quite uncommon unless underwriting requires it. A bank or lender might pull reports from two or more bureaus for cross-verification.
The question remains: Is there an industry standard in India? Which Credit Score Do Banks Use in India?
Why do banks check credit scores?
The answer is quite simple: banks check your loan eligibility by determining your creditworthiness and repayment behavior before approving a loan. If you are stuck wondering, "Which credit score do banks use in India?" There is no universal answer. Some institutions and lenders use a combination of CIBIL with other bureaus like Experian or CRIF High Mark.
TransUnion CIBIL keeps data for around 600 million consumers and 32 million companies. CIBIL is part of an American multinational called TransUnion, which we know as the CIBIL score in India. Because of this unique history and experience, most banks hold the CIBIL score as their primary metric.
Every bureau has a distinct algorithm, formula, or scoring model based on which they calculate your credit score, which depicts your creditworthiness in a numerical representation.
● Any creditor would not want to invest in somebody who is not planning to make repayments towards the loan. For lenders, loans are an investment for which they need assurance of repayment. They check your details to determine if you satisfy the loan requirements, after which they approve or reject your loan.
● This process also finalises your interest rate or the requirement of collateral.
● Lenders also check your existing liabilities. Having considerable debt will affect your capacity to repay any additional loans.
● There are also additional considerations if you require a higher loan amount. They will look into your income and employment stability and require a higher CIBIL score.
On top of that, the credit score is also your first impression, which is used during the “filtering” phase of banks processing loan applications.
So which credit score do banks use in India?
TransUnion CIBIL
When asked, “Which credit score do banks use in India?" remember that over 90% of Indian companies and institutions use the CIBIL score as their primary credit information. CIBIL also uses a specialised scoring model, integrated within the Indian market and finance. It is licensed by RBI under the Credit Information Companies (Regulation) Act (CICRA) 2005.
TransUnion CIBIL was established as Credit Information Bureau India Limited in 2000, then acquired by a global American MNC, TransUnion, which led to its rebranding as TransUnion CIBIL.
Which Credit Score Do Banks Use in India?
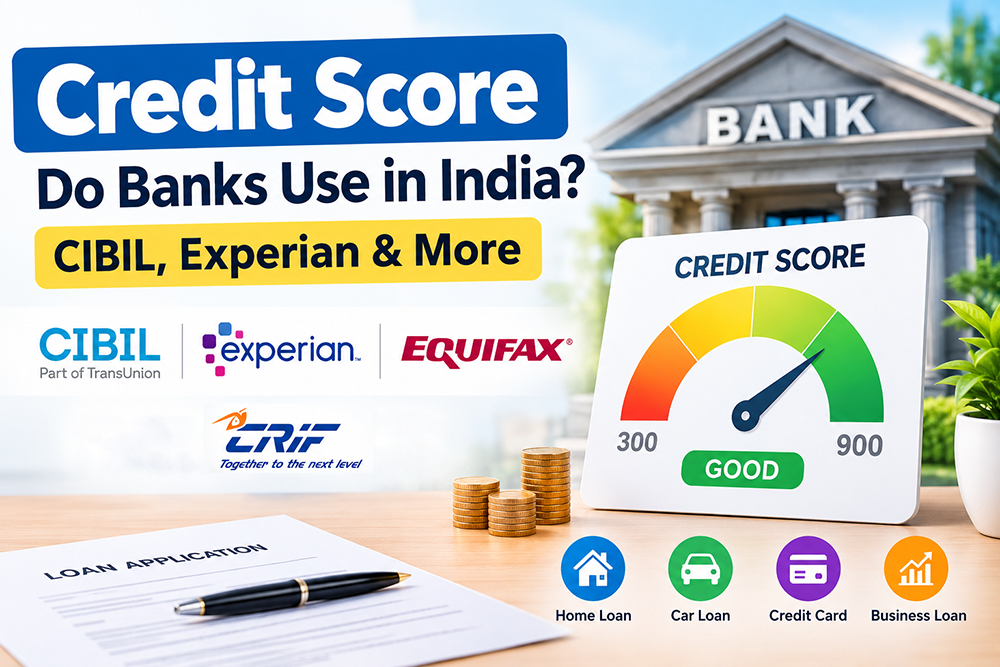
So why do banks consider CIBIL as their primary credit bureau? When evaluating which credit score do banks use in India, we look at the picture below.
Indian banks consider CIBIL as a primary bureau because of its age and mature database of consumers or borrowers. CIBIL maintains records of hundreds of millions of borrowers and receives data from an extensive network of banks, credit card issuers, housing finance companies, etc.
CIBIL
stands as a pioneer of data coverage, industry trust, and a wide network. This
stands as a plausible explanation of why CIBIL is used as a primary agency in
India.
Why do credit scores differ across bureaus?
Many people think they have a common credit score uniform across all credit bureaus in India. In reality, if you find dissimilar scores across CIBIL, Experian, Equifax, and CRIF High Mark, it is completely normal. This happens because credit bureaus operate independently and may not receive identical information from every lender.
There are reporting differences and even differences in how the scores are calculated across each bureau. Some information might be reported in one and might not be reported by the lender in the other. Although lenders are expected to report credit information across all RBI-authorised agencies, the timing and completeness of the reports might vary.
For example, your bank might report your details to CIBIL rather than Equifax. If one has received specific information earlier than the other, the results and reports might differ. Experian is also known to generate faster reports than CIBIL because CIBIL waits to gather information from multiple lenders and institutions in its network.
There
might be differences in the proprietary scoring model and the weighting the
agencies assign to each factor in the credit score calculation. Therefore, the
exact numbers might differ, but there is nothing to worry about. Maintain
healthy credit behavior and habits to get a score within a similar range across
all Credit Information Company reports.
Experian
If you look closely at the resulting picture of which credit score do banks use in India, Experian is a major contender.
Unlike CIBIL, Experian operates in multiple countries and is a globally recognised credit information company. It is one of the world’s big three credit information agencies—alongside Equifax and CIBIL. Experian is headquartered in Dublin, Ireland.
Unlike the property scoring model that CIBIL uses, Experian uses American systems like FICO or VantageScore, depending on the country of operation. It brings an international perspective and expertise into the Indian market. It increased competition among credit bureaus. The factors in the calculation of credit score are similar to CIBIL, like loan repayment, due balance, credit utilization ratio, account history, and age.
Experian’s global presence and advanced data analytics have made it a preferred credit information agency, bringing diversity to the financial market. Many lenders prefer to use it alongside CIBIL or as a primary method.
Equifax
Equifax is one of the world’s oldest credit reporting agencies, dating back to 1899 in the USA. It is headquartered in Atlanta, Georgia. Equifax India was introduced in India with the purpose of bringing comprehensive and diverse credit reporting services to lenders and consumers, thereby supporting responsible lending practices.
Equifax receives data from multiple banks, lenders, and institutions to build detailed credit reports. What distinguishes the CIC is its exclusive focus on the rural and small business lending market, helping financial institutions evaluate borrowers across diverse segments of the economy. Equifax also offers business credit reports and risk management solutions that assist lenders in reducing defaults.
CRIF High Mark
CRIF High Mark might be the youngest player in India’s credit landscape, but it has rapidly emerged to be one of the prominent ones. It was established in 2007 as High Mark Credit Information Services and later became part of CRIF, a global credit bureau and business information company headquartered in Italy. CRIF High Mark received authorisation from RBI and began offering credit reporting services to financial institutions across India.
High
Mark is known for its maintenance of India’s largest databases of microfinance
borrower information. It is also used independently as well as in combination
with other credit bureau reports. CRIF High Mark offers business and consumer
credit information, fraud prevention solutions, and advanced analytics. Today,
many lenders use CRIF High Mark as a reliable solution.
Conclusion
As far as the question of “which credit score the banks use in India” is concerned, there is no universal answer to it. Nevertheless, TransUnion CIBIL continues to be the most recognized market credit bureau used by banks, NBFCs, and credit card issuers. The experience, large database of borrowers, and widespread usage in the industry have helped the CIBIL score become the industry standard used by many lenders.
However, Experian, Equifax, and CRIF High Mark are also RBI-authorized credit information companies and are widely used by lending institutions. Moreover, many banks use reports from a combination of credit bureaus in order to get an insight into the borrower's behavior and financial status.
Consequently, people must remember that relying only on the CIBIL score may be unreasonable in the borrowing process. One must consider all credit bureaus within a comprehensive picture for the question “Which credit score do banks use in India?" Individuals need to pay attention to their overall credit scores in every credit agency, make payments timely, maintain a low credit utilization rate, and monitor their reports for mistakes.
In the end, whatever credit bureau the lender uses, responsible borrowing and repayment behavior will determine whether a person gets the loan or not.
Read Also: Hard Inquiry vs Soft Inquiry: Difference and Impact on CIBIL Score
FAQs
1. Are credit scores similar in all credit reports?
Generally,
the credit scores fall in the same range across all bureaus. At the same time,
it is wrong to say they are identical. This is because of incomplete reporting,
different scoring formulas, timing delays, and unique errors. Small score
differences of 20 to 50 points are normal across bureaus.
2. Who are data furnishers?
Data furnishers are the entities responsible for sending consumer credit information and updates to credit bureaus. These are banks, NBFCs, housing finance companies, credit card providers, micro-finance providers, and other lending organizations.
They
provide data regarding the loan balance, repayment record, defaults,
settlements, write-offs, account status, and other information on a regular
basis. The information provided is used by credit bureaus for preparing the
credit report and calculating the credit score.
3. How many credit bureaus does a bank refer to?
Several
banks and lending institutions access information from more than one credit
bureau, especially for large loans like home loans, business loans, and
commercial finance. This ensures that the information is verified and also
provides a more comprehensive picture of the applicant's creditworthiness.
Combination credit report checks are meant for cross-checking.
4. How frequently do the credit bureaus update the credit reports?
The
credit reports are updated based on the monthly new account information. The
exact period may vary based on the process followed by the lending organization
and the credit bureaus.
5. Can I view my credit score without affecting it?
Yes, checking your personal credit score is counted as a soft pull and doesn't affect your credit score.
6. Which credit score do banks use in India?
Banks
use the CIBIL score because of its vast database, history, and experience.