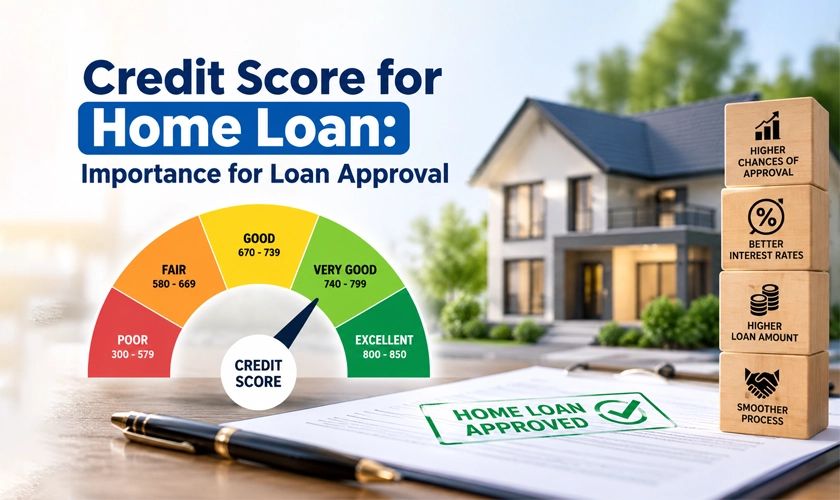
Credit Score for Home Loan: Importance for Loan Approval
The
purchase of property in India is not a simple deal but involves years of
careful planning in financial matters. Credit score is a key criterion in all these
complicated aspects of the loan deal. However, in the case of a home loan,
there is a slight difference.
The
importance of credit score for a home loan becomes more obvious due to the
nature of this loan, as being a larger loan amount has a longer tenure and has
increased responsibilities. This indicates the need for the lender to evaluate
your financial risk for a longer period of time.
Why is the CIBIL score significant for a home loan?
Having a good credit score for a home loan will improve the chances of having a home loan approved. A good credit history is important due to its crucial role in reducing the financial risks for the bank. Financial risks differ from short-term risks due to the nature of the loan. In this case, the most important thing for the lender is to be sure about a reliable income source. It can sometimes be as important, or even more important, than having a good CIBIL score of 750.
Why? Because long-term credit is vulnerable to economic changes, inflation, and the repayment capacity of the borrower. There is a lot of uncertainty and a risk of interest rate changes due to rising inflation.
Importance in loan approval
A good CIBIL score represents your repayment capacity and thus makes the lending institution comfortable with your loan application. Loan applications with a poor credit score for home loan will definitely be rejected by the lending institutions because the risk factor is evaluated in addition to the tenure of the loan. It may even result in getting you a smaller loan amount, paying a higher down payment, or more stringent terms and conditions from the point of view of the lending institution.
Interest Rate
A good CIBIL score indicates that there is low risk involved for the lending institution and therefore lower interest rates. As the home loan is provided for a long tenure, even a small interest rate increase will mean compounding of the same over the years. A good credit score for home loan means a lower interest rate.
A real-life calculation is illustrated below, in which an applicant has applied for a 50 lakh loan for 20 years' duration:
Good
CIBIL score: 8.5% interest rate, EMI per month: ₹43,391
Poor CIBIL score: 10% interest rate, EMI per month: ₹48,251
Total interest paid for A is ₹54.14 lakh, and for B it is ₹65.80 lakh, and the total amount paid is ₹1.04 crore for A versus ₹1.16 crore for B. Also, there is no fixed interest rate no matter what your CIBIL score or financial standing is—it still ultimately relies on the lender’s policies, loan-to-value ratio, or decisive factors presented by you.
Loan amount and long-term affordability
This is arguably the most important factor for home loans. Even though you might be approved for either loan smoothly, you might not be approved for a home loan because it is a larger amount. Even if you were, since you require a higher amount, you might not receive the desired amount. This can create complications since the lender doesn't only look at the property itself.
Loan negotiation and tenure
A higher CIBIL score shows responsible credit management. This strengthens your position for negotiation with the lender because of increased confidence. You can negotiate a better interest rate or compare offers by lenders. Other charges eligible for negotiation with a high credit score for Home Loan are:
● Processing fees
● Administration charges
● Documentation-related charges
● Loan transfer or refinancing
Benefits of a High CIBIL Score for a Home Loan
A high credit score for Home Loan can be really helpful while applying for a home loan. Credit scores act as one of the various parameters that lenders consider to determine your past repayment behavior, financial discipline, and the risk associated with lending money to you.
Thus, a good score might increase the probability of your loan being approved and may even help you get better terms for your loan. However, apart from the credit score, factors such as income stability, your current financial commitments, age, the nature of the property, and others may also matter.
Better chances of home loan approval
The
most significant advantage of having a high credit score for home loan is that
it makes it easier for you to get your application for a home loan approved.
This happens because a good credit score is indicative of your good repayment
history and credit discipline. Any lender will be happy to know this
information about you. A good CIBIL score is generally considered to be
anything above 750.
However, even with a great CIBIL score, the loan will not necessarily be approved, as the lender might look into other aspects of the loan application process, such as your income, any existing EMIs, your employment/self-employment status, age, value, and location of the property, among others. Consequently, consider having a good credit score as just one of the major benefits rather than an assurance of getting the loan approved.
Negotiation power
Having
a great credit score for home loan is also a big bargaining point while
negotiating a home loan with the lender. This is because a good CIBIL score
implies that there is strong creditworthiness, and therefore lenders are
comfortable with lending under competitive terms. Information on home loan
eligibility reveals that great credit scores can lead to competitive interest
rates and loan terms.
A high credit score for home loan can come in handy when you are eligible with several lenders. You can use this opportunity to negotiate terms with lenders in a bid to get a competitive deal based on your credit history.
Smooth loan processing
Having a good credit score for home loan shows that your credit has been properly managed till now. In fact, since the score is used by the lender to gauge the extent of regular payments and sound credit management practices, keeping it high can be helpful for a strong home loan application.
That said, a good score would not necessarily help you avoid the various other steps involved in the loan approval process. You will still have to meet all the lender’s criteria related to documentation, earnings, property, and eligibility. Thus, combining a high credit score for home loan with proper documentation, income, and manageable debts can make sure that your application is in order.
Higher eligibility and loan amount
Your CIBIL score also influences the amount of the home loan as well as your eligibility for the same. The higher your CIBIL score, the more likely you are to be eligible for a larger loan amount, whereas a poor score can reduce your eligibility to a lower loan amount.
However, just having a credit score for home loan is not enough for obtaining a certain amount of finance. The home loan amount also depends on many other things, like the value of the property, the profile of the borrower, the lender, the stability of the income, and existing financial commitments. A strong credit score for home loan is beneficial with sufficient repayment capacity and healthy finances.
Potentially lower interest and other fees
Even the interest rate charged by the lender on a substantial amount of money for a home loan can make a big difference to the total borrowing cost of a home loan. A high CIBIL score will help you get a good deal on home loan interest rates, as the score reflects creditworthiness. The current guidelines issued by the lender state that the interest rate offered is one of the aspects that can be affected by the credit score of the borrower.
Applicants who possess a strong profile can benefit from a good negotiating position to get favorable terms, depending on the policies of each lender. It would be a mistake to think that a high credit score for home loan will reduce all kinds of fees. It is always necessary to compare the interest rate, processing fees, and other related costs charged by different lenders while deciding on which loan to take.
Flexibility when comparing lenders
It will increase your choices while looking for a home loan when you have a high CIBIL score. As different lenders set their own credit-score standards and lending criteria, having a strong credit score for home loan helps you to become eligible for a home loan with many different banks rather than being restricted by a weak credit history.
Long-term financial savings
In the same vein, a good credit score for home loan can also play a role in helping you save in the future, especially when you get a home loan at a competitive interest rate through a good score. Good scores mean better chances of getting better rates.
Since getting a home loan will involve spending money in a big way, it should be of equal importance for you to consider how much interest you will pay when taking up this financial obligation. Keeping a good credit record before you apply is sure to help you get a better chance of making a comparison of your options and choosing the right one.
What are the other factors examined by the lender?
● Monthly Income
● Stable income source or
employment
● Existing EMIs/debts
● Income tax returns
● Years of work remaining
● Loan-to-value ratio
● Previous debts and repayment
history
● Bank account statements
● Debt-to-income
● Property value
FAQs
1. Is there an ideal credit score for a home loan?
While there is no standard, fixed minimum credit score for home loan, you will need a minimum CIBIL score of 700. This is because you need good to excellent credit repayment behavior to get approved for long-term borrowing and a higher loan amount. This is why an ideal score would be 750-800, and 800+ is even better.
2. How can I raise my CIBIL score by 100 points in a month?
Gaining 100 points in credit is extremely unrealistic for a timeline of 30 days unless it's due to a major reporting error or artificially increased CUR. But you can make desired or satisfactory progress within 1 to 3 months.
● Pay your bills on time and
close your debt accounts
● Use a mix of credit
● Maintain CUR less than 30%
● Maintain your oldest credit
cards
● Monitor and check for credit report errors
Read
More: Can my credit go up 100 points in one month?
3. What documents should I prepare for a home loan?
● Application form
● Salary slips
● Identity Proof
● Address proof
● Photographs
● Income tax returns for
self-employed
● Bank statements
● Passport copy
● Property documents
Note
that documents vary for each applicant depending on their employment type,
income, and individual conditions.
4. What can I do to get my home loan approved?
● Improve your credit score and
profile
● Lower your debt-to-income
ratio
● Maintain stable employment
and optimum income conditions
● Prepare documentation and a
down payment
● Clear debt and liabilities