CIBIL Score Variation Across Websites and Apps: An Explainer
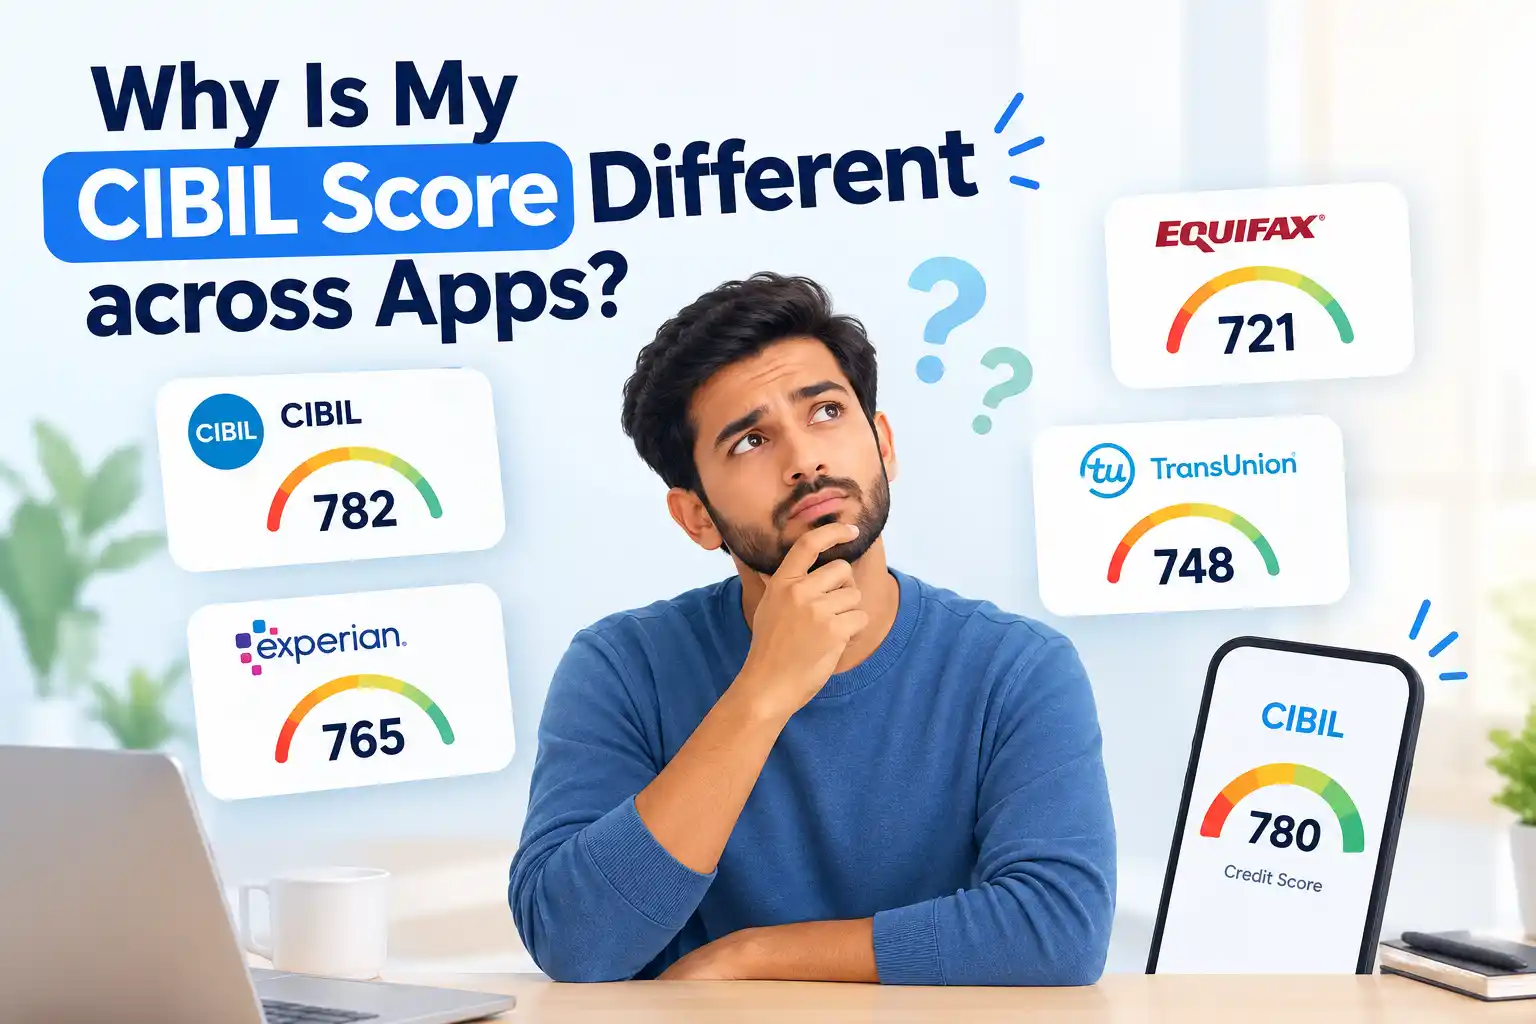
In today’s credit ecosystem, everything is digital, and credit score checks have become easier than ever. A wide range of credit score apps in India and other digital offerings allow consumers to check their credit score for free. However, users face confusion regarding CIBIL score variation across websites. One app may show 670, another shows 689, and one shows 696.
It might be astounding at first, but the truth is that it is completely normal. Different bureaus have different scoring models and cause operational discrepancies in what they show us. The truth is that this difference is always trailing the other instead of maintaining a large gap.
This guide explains why CIBIL score variation across websites occurs and how credit score apps in India generate reports.
What is a CIBIL score monitoring app?
A credit score monitoring app is a platform that allows users to access and track their credit score and report to analyse their credit health. These applications act as intermediaries between consumers and credit bureaus, providing access to credit scores and credit insights.
Most modern credit score apps in India offer much more than simply displaying a score.
●
Regular credit score updates
●
Credit report summarisations,
e.g., credit usage
●
Personalised loan recommendations
●
Identity theft alerts
●
Loan and credit card eligibility
assessments
Many platforms market themselves as a free credit score check app, because users can access their credit report directly without purchasing. They deal with data processing, insights, and recommendations. These apps generate revenue on a partnership model with lenders, bureaus, financial institutions, and marketplaces. Credit score apps in India connect with the four main bureaus: TransUnion CIBIL, Experian, Equifax, and CRIF High Mark.
However, the truth is, none of the apps or
bureaus are the most accurate; it varies based on the data they use to process
the reports. In India, CIBIL is the most reliable and commonly used CIC.
It is the oldest and holds the largest consumer and commercial database for
banks.
How do credit score apps in India generate reports?
The process of understanding how credit score
applications work in generating scores will enable the reader to understand the
disparity in score.
Financial Information Gathered by Credit Bureaus
There are four licensed credit bureaus in India, namely
TransUnion CIBIL
Experian India
CRIF High Mark
Equifax India
This financial information comes from banks, non-banking financial companies (NBFCs), credit card companies, and housing finance companies, among others, and entails information such as:
●
Amount of loan
●
Payment history
●
Credit balance
●
Utilization
●
Defaults on loans
●
Credit inquiry
● Age of account
Every credit bureau has its own database with
updated information depending on the information fed from the lenders.
Apps Collaborate with Specific Bureaus
Different apps use different bureaus for calculating scores. Some may get the score from TransUnion CIBIL, while others get their score from Experian or CRIF High Mark.
This means that because each bureau has some different information about an individual, it is normal for the scores to be different.
If the lender feeds information to one bureau
earlier than another, then this difference would affect the scores generated by
different apps.
There Are Different Scoring Models
The factors considered by credit scoring models include:
●
History of payments
●
Amount of debt
●
Length of credit history
●
Mix of credit products
● Inquiries
These models give different weights to these
factors, hence causing some slight variation in the scores despite using
similar data. Every bureau has a distinct model despite having similar factors
for consideration.
Timing of Updates Makes a Difference
Credit reports are not static but rather dynamic.
While one bank may update the payment status
today, another may do so in the coming week. While an app updates its data from
the bureau daily, another may update monthly.
The implication is that there will be CIBIL score variation across websites for the same person based on the timing of data updates.
My credit score is different across apps: Reasons
Many consumers search online for answers to
this question: “Why is my credit score different across apps?”
Different credit bureaus are being used.
This is the most common reason. Every credit score provider connects with different bureaus, one or a combination, but not each bureau. Every bureau has different scoring algorithms, update patterns, and access to different data based on what, which, and how lenders choose to update them. This independence doesn't automatically mean that one bureau is more accurate or wrong compared to the other.
You may unknowingly check scores from
different bureaus and formulas, which causes this CIBIL score variation across
websites.
Timing of Data Updates
Data in the credit report changes frequently since the banks provide updates.
For instance, if you just finished paying back your credit card balance, one bureau will get the data immediately while the other will get it some time later.
In such situations, different apps may show
CIBIL score variation across websites.
Different Scoring Algorithm
Each credit bureau calculates scores based on proprietary algorithms.
While the credit data may be equal for both
bureaus, the score may still differ due to different calculation formulas.
Consequently, the risk perception by different bureaus is slightly different.
Partial Reporting from Lenders
Not all lenders report to all credit bureaus at the same time. The loan account reflected in one bureau may not be visible yet in another bureau.
These differences can affect scores shown in
various credit score apps in India.
Difference in Score Refreshing Time
Credit score apps in India update credit scores as per their own app refresh schedules rather than in real time.
If your score was refreshed on one platform
yesterday but on another two weeks ago, there will probably be a noticeable
difference, causing CIBIL score variation across websites.
Multiple Versions of Credit Scores
There are several versions of scoring models
developed by credit bureaus.
For example:
●
Credit card lending models
●
Personal loan models
●
Auto loan models
● General consumer credit models
Depending on which free credit score check app
you choose, the number may differ.
Top Credit Score Apps in India and Their Bureaus
You should look for the following benefits in your free credit score check app:
●
Free service
●
Multiple or combination bureau
reporting
●
Faster updates
●
Personalised recommendations
●
Other financial services
PaisaBazaar
It brings your free monthly score from multiple credit bureaus in India—in fact, all four bureaus in India. You can access it in your regional language and enjoy AI insights, a score simulator, and many personalised product recommendations. These features are unique compared to other apps.
PayTM
PayTM is not only a digital payments app but
also provides credit monitoring services. Users gain financial insights,
monitor and analyze their credit score, and get personalised recommendations.
It all centers around convenience, the unique idea of making payments along
with credit health and monitoring..
OneScore
It offers the Experian credit report and
CIBIL, which might be the paid alternative. Its exclusive feature is the Score
Planner, which is a personalised roadmap towards a better credit score. It
provides alerts for notifications and updates, an AI credit coach, weekly
Experian updates, credit history, and tools for error identification.
My CIBIL
It only provides the TransUnion CIBIL score,
providing direct access to the most-used CIBIL score and report. One can also
report disputes directly in case of any credit report errors. Subscribed users
also get credit alerts and a score simulator.
Bajaj Finserv
Bajaj Finserv combines free credit score checks from Experian and CIBIL, monthly score updates, an active and closed accounts overview, and a credit score simulator. You can also dig deeper into your credit report insights and credit score factors. It also provides an EMI calculator and shows pre-approved offers.
Common misconceptions about CIBIL score variation across websites
A few myths lead to unnecessary fear for
borrowers.
Myth 1: One of the Scores is Incorrect
Not always. Scores can vary as long as they come from different agencies and associated scoring models. This CIBIL score variation across websites is normal.
Myth 2: App Distorts Credit Scores
Credit score apps do not just distort your
credit scores. They display scores that come from the credit bureaus that they
have access to and are partnered with.
Myth 3: Checking Scores in Several Apps Affects Your Credit Score
Nope.
Self-checking your own credit scores is
classified as a soft inquiry and does not affect your credit scores. No matter
how many apps you check yourself, self-checking usually has no effect on credit
scores.
Myth 4: Only CIBIL Credit Scores Matter
Yes, CIBIL is the most trusted credit score in India, but the following scores may also be considered:
●
Experian
●
Equifax
● CRIF High Mark
Banks may have preferences when considering
the report of one credit bureau rather than another. One must not rely on only
one bureau because complete visibility and understanding of your credit profile
is also important. Not all lenders report to every bureau—so some of your
activity might be invisible to a specific bureau or combination of bureaus.
Myth 5: Major Score Fluctuations Always Point to Fraud
Not necessarily. Moderate score fluctuations normally arise due to bureaus' differences, timing of reporting, and scoring formulas. A 20 to 50-point score difference is normal.
Nevertheless, when you see major discrepancies
or unknown accounts in your report, it would be wise to scrutinize all bureaus'
reports and file a dispute.
Myth 6: Better Score in One Application Means Loan Approval
The loan approval process is about much more than credit score.
In addition, lenders check your:
●
Income stability
●
Work history
●
Other obligations
●
Debt/income ratio
●
Ability to repay
Conclusion
CIBIL score variations across websites and applications are quite common. Indian credit score applications may collaborate with diverse credit bureaus and use various scoring models and update periods. Hence, small variations in scores should be considered normal.
As an alternative to trying to have identical scores on all platforms, people should concentrate on maintaining good credit practices and getting regular reports. A reliable application for checking your credit score for free will be helpful in detecting problems and improving your financial status.
Consistency in repayments and proper use of
credit matter much more than small discrepancies between various scores. On a
final note, accept the discrepancies as a result of a dynamic score rather than
a fixed score.
FAQs
1. Can I control this discrepancy across credit scores in
bureaus?
Yes, you can control this difference if it arises from a credit or factual error. However, normal CIBIL score variation across websites is a result of standard algorithms and can't be matched.
2. Which credit score app in India is most accurate?
Apps that give users their credit scores
should be those that give details on information collected from credit bureaus.
Accuracy is more dependent on the bureau and the updates provided by lenders
rather than the apps themselves.
3. Does using the credit score check app to check my score lower my CIBIL score?
No, checking the CIBIL score by oneself is a
soft pull and is therefore not likely to affect the credit score.
4. How much of a discrepancy in credit scores among different apps is acceptable?
There is nothing wrong with discrepancies in
credit scores among various apps since there are many bureaus and score models.
This gap can be anything from a 20 to 50-point scale.
5. Are there scores other than CIBIL that can be used by the lender?
Yes, other bureaus like Experian, Equifax, and
CRIF High Mark scores may also be used by lenders.