A joint personal loan is a great asset, as it
shares the responsibility between both applicants, for example, a couple. Not
only does it make managing finances easier, but it also reduces stress and even
combines both of their credit scores for better offers. What they are offered
initially is significant for the entire repayment process. This is because it
influences each and every aspect, starting with compound interest, tenure, and
how you plan to finance the monthly installments.
A joint personal loan is a practical solution towards a comfortable life for you and your spouse or children. Therefore, what comes first is understanding the co-applicant CIBIL score impact.
What is a co-applicant, and how does a co-applicant CIBIL score impact work?
A co-applicant is a person, like a spouse, parent, or business partner, who co-signs a loan or financial agreement on a joint home or personal loan. There are also other kinds of joint loans, like joint auto loans or loans against property. Both parties are legally and equally responsible for repaying the loan. Common co-applicants include:
●
Spouse
●
Children or parents
●
Business partners
● Siblings
This is where the co-applicant CIBIL score impact comes into play.
●
CIBIL scores of both applicants
●
Repayment history
●
Credit card usage
●
Existing loan applications
●
Income stability
●
Debt-to-income ratio
● Employment profile
These are important points for a lender.
If both applicants demonstrate responsible
credit behavior, the lender perceives lower risk. If there is a history of
missed payments or defaults, even on just one applicant, the lender views the
entire application as risky. However, there are ways you can compensate for
it—like a co-applicant having a clean and disciplined credit history, high
income, or a strong credit score.
Is it a co-signer, a co-applicant, or a guarantor?
When it comes to a co-applicant, you might be thinking of a co-signer or a guarantor. This is an area of confusion for many borrowers. Many use these terms like "guarantor" or "co-signer" interchangeably, which is not technically correct. These terms are not always the same from a lender’s perspective.
The difference matters because each person carries a different level of responsibility for the loan, and each can be affected differently, so repayments can become a problem. Let’s look at it virtually.
You apply for a joint loan with your brother. Both of your incomes are considered, both of your credit scores are reviewed, and both of you are equally responsible for repaying the loan. In this situation, your spouse is acting as a co-applicant.
Now imagine your brother wants a loan, and his profile is risky to the lender, who is hesitating. The lender may ask for someone with stronger credit to support the application. If you agree to step in and take responsibility if your brother fails to repay, you may be acting as a co-signer or guarantor, depending on how the lender structures the agreement.
Read more: Co-signer vs. co-applicant
Co-signer
In some lending systems, a co-signer is the person who agrees to take responsibility if the main borrower fails to repay. They may not be borrowing the funds themselves but provide additional assurance to the lender. Their liability comes early, from day one of default. They often have ownership rights, and the debt may appear on their credit score. It might also impact their score negatively or positively and raise a hard inquiry.
●
Strengthens the application
●
Does not usually receive or use
the loan amount
●
Becomes responsible if the
borrower defaults
● Can see their credit negatively affected by missed payments
Both terms' usage can be similar depending on
internal policies, though in most cases they are used in different situations.
Guarantor
A guarantor acts as a financial backup, and their role begins when the borrowers fail to meet repayment conditions. Their liability is only considered a last resort when the borrower has completely exhausted all the lender's collection efforts. They have no ownership, and neither do they have or exercise any immediate impact on the credit score. However, this may hurt their credit score if the lender pursues collection from the guarantor.
●
A guarantor promises to repay if
the borrower defaults
●
Provides additional confidence to
the lender too
●
Counts as a hard inquiry
●
May face legal and financial
consequences if the loan remains unpaid
Co applicant
A co-applicant is an joint borrower. The income, debts, employment details, and credit score of the co-applicant are all reviewed during the loan sanctioning process. A co-applicant is only one of the three who receive the funds, property, or asset ownership along with the main borrower. However, both parties involved here are the ‘main’ or ‘primary’ borrowers.
In the case of an co-applicant:
●
He is equally responsible for
repayment
●
Will help in improving the loan
eligibility
●
The co-applicant CIBIL score
impact is visible
●
Can increase the sanctioned loan
amount
●
Gets impacted by any delay in EMI
payments
● Gets the loan mentioned in the credit report
Why would you need a co-applicant on a personal loan?
Depending on your financial situation, you
might need help in the following areas:
To improve loan eligibility
Suppose your monthly income is just a few thousand away from qualifying for the desired amount. By adding a spouse or parent with a stable income, your combined earnings increase, improving your chances of approval.
If your income is ₹65,000 and your spouse
earns ₹32,000, your combined income crosses the required threshold of ₹80,000.
From the lender's perspective, the repayment capacity becomes much stronger.
To get a higher loan amount
At times, an individual may be eligible for a loan but may not qualify for the amount he requires.
A co-applicant may be of great assistance in increasing the sanctioned amount since the lender assesses the repayment capacity of the family instead of an individual's income only. This is especially helpful in case of:
●
Medical emergencies
●
Household renovations
●
Wedding costs
●
Loan consolidation
●
Education financing
To improve approval chances
A person with a low credit history has trouble
getting approval on his own. A disciplined co-borrower with a good CIBIL score
makes an application stronger. This is one of the best cases where the
co-applicant's CIBIL score helps, especially for higher-than-average loan amounts.
To access better interest rates
Most borrowers do not realize how much a
credit score affects interest rates. A good combination shows less risk, which
may fetch better loan terms. A small difference in interest rate leads to
significant savings over the long term due to compound interest. Some providers
set a much higher-than-average market interest rate.
To build a credit profile
Some young people with little or no credit history end up becoming co-applicants with parents or a spouse. With repayments being made, they start building their own credit profile and build history gradually at their own pace.
What does the lender see when you have a co-applicant on a personal loan?
Adding a co-applicant is not a magic potion;
the lenders still have to review a few points. This greatly changes the
application dynamics compared to individual loans.
Shared responsibility
The first thing lenders evaluate is shared
liability. Both applicants become responsible for repayments. This
significantly reduces lender risk because repayment does not depend on a single
source of income. If the primary borrower faces job loss, the co-applicant can
still take over the responsibility instead of defaulting entirely. Not only
that, but a single missed payment will affect both applicants' credit scores.
This is an enhanced layer of security for co-applicant CIBIL score impact.
Income
Income has the strongest influence on loan approval. Lenders evaluate:
●
Monthly salary
●
Business income
●
Company profile
●
Employment stability
●
Industry profile
● Working years
A combined income is still seen as one source
of the loan funding; this is one of the main advantages of a co-applicant CIBIL
score impact.
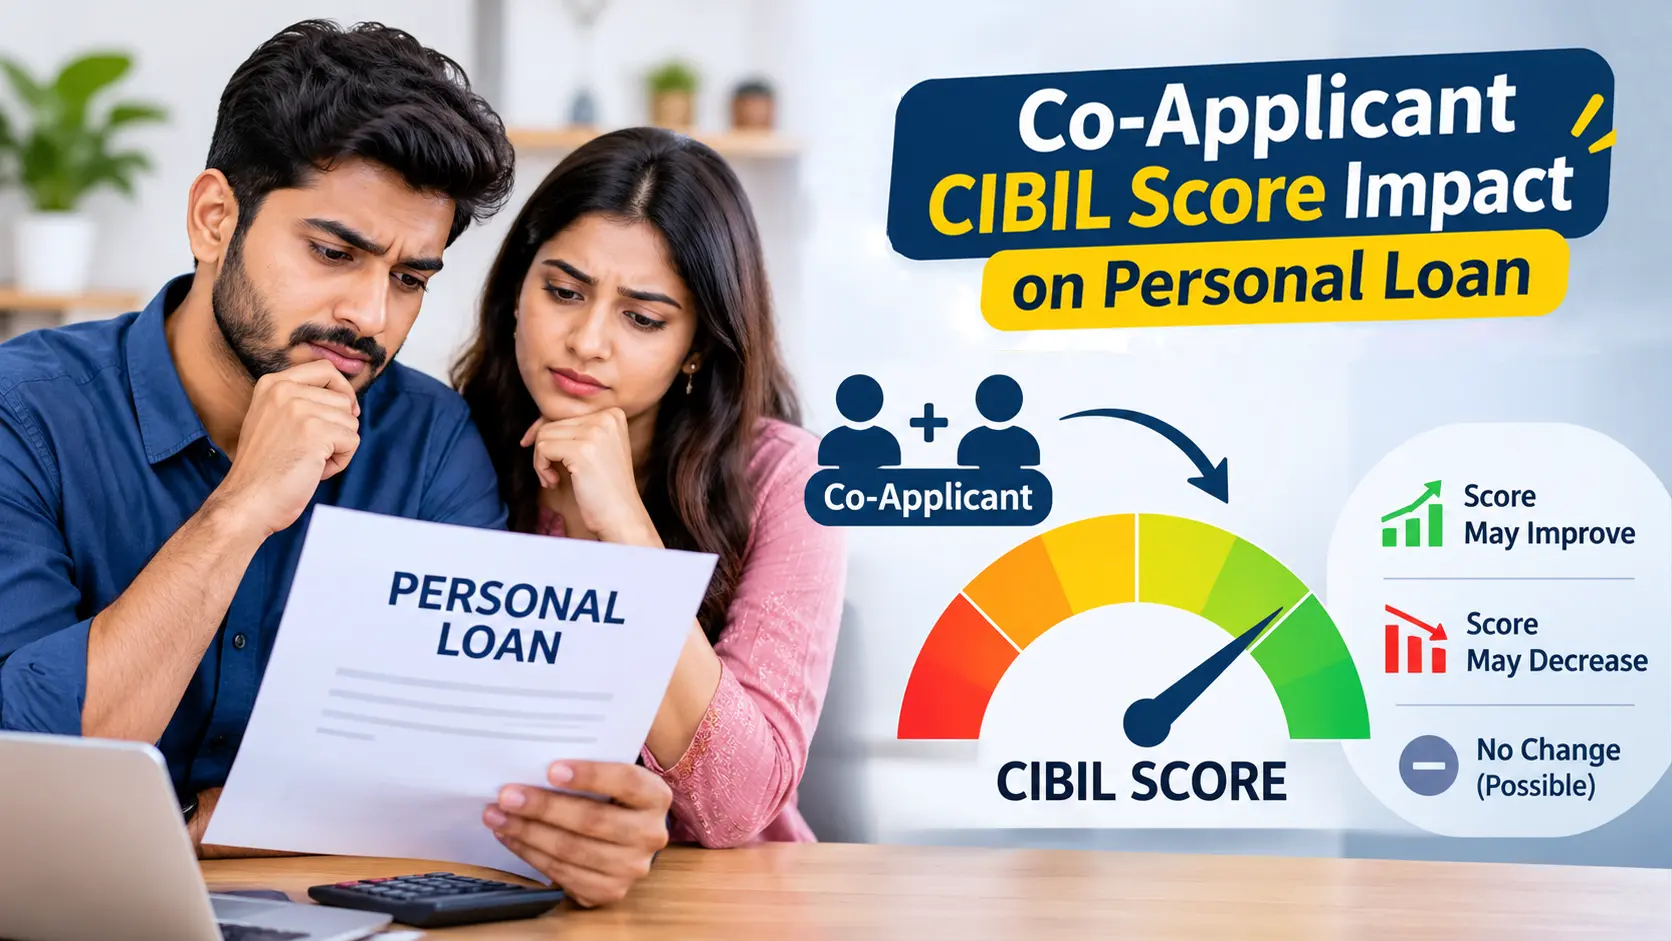
Co-applicant CIBIL score impact
Now here’s the tea you are waiting to sip:
co-applicant CIBIL score impact. Lenders do not evaluate a single person’s
CIBIL score or report. When both scores are strong, the lender perceives a
low-risk profile and positive credit behavior. When one score is good while the
other is average, there are chances of scrutiny before approval. If one score
is poor, even if the other is excellent, that triggers a warning sign.
Credit card utilization
Many borrowers do not realise how closely
lenders examine credit card usage. This directly affects how the joint
borrowers will repay their debt from available funds. This is why lenders
examine both the applicant’s credit usage and look for a healthy 30-40% credit
usage.
Defaults and existing loans
Previous defaults are the strongest red flags for lenders. They review
●
Loan defaults
●
Credit card defaults
●
Write-offs
●
Delayed EMI payments
● Settled accounts
If even one of the borrowers has a history of
missed payments or multiple other loan obligations, the lender may show
scrutiny over the risk involved.
Debt-to-income ratio
The debt-to-income ratio is the amount of your income you need to dedicate toward existing debt obligations. Lenders pay close attention to the debt-to-income ratio, especially for larger ticket loans.
DTI = TOTAL MONTHLY OBLIGATIONS/MONTHLY INCOME x 100
Example:
Monthly income: ₹80000
Car loan: ₹20000
Consumer loan: ₹12000
DTI: ₹32000/₹80000 x 100+ 40%
According to major banks, a 36% DTI is required, while 40% is borderline. A healthy DTI is comfortable for both parties and the lender and shows healthy debt/financial management.
Positive Co-Applicant CIBIL Score Impact
The inclusion of a co-applicant can make quite a difference provided it is done in the right way.
●
Increased Possibility of Approval
●
Increased Borrowing Limit
●
Enhanced Loan Terms
●
Financial Safety Net
●
Effective Credit Building
Negative Co-Applicant CIBIL Score Impact
●
Late Payment Affects Credit Report
of Both Applicants
●
One poor credit score impacts the
entire application
●
Joint Liability
●
Impact on Future Borrowing
How to decide if I should add a co-applicant or not?
The CIBIL score of your co-applicant is very important for your personal loan. You might also consider your requirements and individual credit profile.
You should consider a co-applicant if:
●
You need a higher loan amount,
which reduces the overall stress and burden
●
Your income is insufficient, and
you need help matching the income threshold, even just by a tiny bit
●
The co-applicant has a strong and
stable credit score
●
Remember that you will be sharing
and managing finances together, so you should check the compatibility or mutual
understanding in this regard, especially in the long term
● You want improved approval as well as interest rate offers
You don't need one if you already have a high income and qualifications on your own. If you think the co-applicant’s credit score or credit history is not good enough, you can disregard this option. In case of a lack of understanding or willingness to share legal liability and responsibility, one should be wary of a joint application for a personal loan. You should understand that the co-applicant's CIBIL score impact can strengthen or weaken based on mutual financial health.
Read More: Improve credit score before loan application
Conclusion
A joint personal loan can be an excellent financial tool when used responsibly. It increases borrowing power, improves eligibility, and may even lead to more favorable loan terms. However, this changes the overall dynamics a lot, and there is a mutual dependence on each other’s financial profiles.
The co-applicant CIBIL score impact extends
far beyond simple loan approval. It influences interest rates, loan amounts,
lender confidence, future borrowing opportunities, and repayment flexibility. A
poor combined profile may cause challenges or even unforeseen discomfort.
Taking these steps after a careful review of the article will greatly benefit
both of you in protecting your long-term credit.
FAQs
1. Does a co-applicant CIBIL score impact personal loan approval?
Yes. The creditworthiness of both applicants is assessed by the lender. If the co-applicant has a good credit profile, it can help your application, and if not, it can have an adverse effect.
2. What is the minimum credit score for a co-applicant?
Usually, anything over 750 is regarded well by the lenders.
3. Am I able to get a personal loan if my co-applicant has a poor CIBIL score?
Yes, it may be possible; however, you may face some difficulties with approval, or your lender may offer you higher interest rates.
4. Will missing EMIs affect both of us?
Yes. Because of the joint ownership of the
personal loan and any assets, any late or missed payments will affect the
credit report of both the borrower and his/her co-applicant.
5. Is there a difference between a co-applicant and a guarantor?
Yes. The co-applicant is responsible for loan
repayment, like the borrower, and the guarantor usually becomes responsible for
that only in case of default of the borrower.