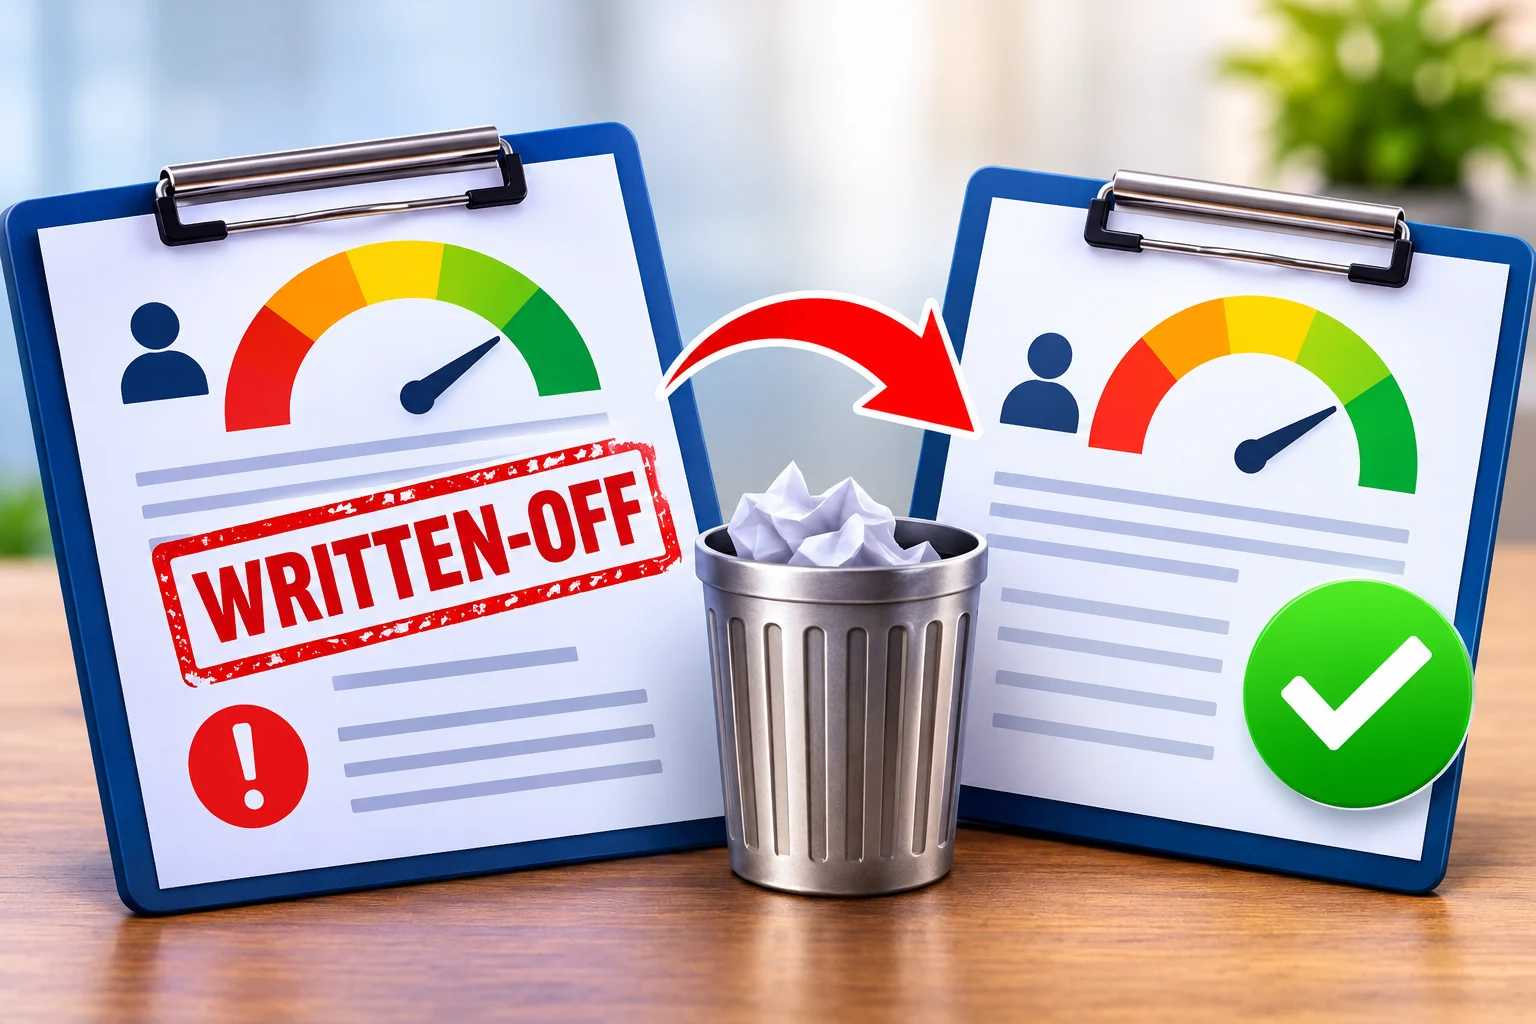
‘Written off” is not a forgiven or clean debt. A write-off is actually an internal accounting or regulatory action by the lender. After a period of 180 days, or 6 months, the lender moves the bad debt to active receivables, which serves as a loss for tax and bookkeeping purposes. Congratulations, you are still legally obligated to pay the amount written off. Even if the debt was written off, the borrower’s due amount still accrues interest, fees, and principal.
So does the lender ignore their loss? They might move the debt to the collections department, file a lawsuit, or collect it themselves. This could end in a bankruptcy, settlement, full repayment, or the creditor's voluntary debt release.
In opposition to what consumers misinterpret, a ‘written-off’ status is quite a serious matter in the authorities’ eyes. So, how to clear written-off in CIBIL?
What is Written-Off? Written-off meaning in CIBIL
A written-off in a CIBIL report is tagged when a person fails to repay a debt for 180 days or 6 months, as it is classified as a non-performing asset. In the lender’s books, it becomes a difficult-to-recover loss. It appears under the account status section in the CIBIL report and stays in the history and report for 7 years for the lenders to evaluate. The NPA status is tagged at the 90-day point of non-activity.
Some people think that it is a forgotten and forgiven account. True, the bank has removed that loan from its internal data because it thinks that it is too difficult to recover that amount. In the background, as the bank has cleaned its records, the dangerous interest and penalties continue to accumulate, and collection actions might take place. At some point, it is bound to bounce back. It is not possible to expect things to end forever at this account status. It might even end in bankruptcy.
It can vary across individuals—as only the principal amount is due or the complete due amount, including interest. Many people wrongly assume Non-Performing Asset (NPA) to be a written-off account.
Non-Performing Asset (NPA)
Generally, a loan turns into an NPA when repayments get overdue beyond a certain period, which usually stands at 90 days. Once the lender marks the account as problematic, it starts making efforts to recover the debt.
Written-Off Account
If the account goes unpaid for a few more months and recovery seems hard, then the lender writes it off as a written-off account.
It simply means that:
● NPA is the first stage of extreme delinquency.
● Written-off is the next stage, in which the lender treats the debt as a probable loss.
However, although the loan is written off for accounting purposes, the repayment responsibility of the borrower persists.
What Does Written-Off Show Up as on a CIBIL Report?
In a CIBIL report, the written-off status appears in the account details section under a loan or credit card account. Some common remarks that may be found:
● Written Off
● Written Off and Settled
● Post Write-Off Settled
● Principal Written Off
● Total Amount Written Off
These remarks act as signals for prospective lenders regarding any repayment problems in the past.
Whenever banks scrutinize a person's loan application, they consider credit behavior carefully. A written-off status in credit history signals high-risk behavior.
Impact on CIBIL score
A written-off status can lower your credit score by 50 to 100 points. For those with a prior good credit score, like 700, it could even drop more, up to 150 points. It can occur due to serious life problems, like income cut-offs, unemployment, medical crises, etc. A written-off status stays on your CIBIL report for seven years, even after paying in full. Even after these 7 years, this history can be accessed by the bank.
Most of your recent applications for loans or credit will be rejected automatically by banks and NBFCs. Even if you qualify for a select few, you will face higher interest rates. So how to avoid this CIBIL impact and how to clear written-off in CIBIL?
How to clear written-off in CIBIL?
A written-off account can't be simply removed or cleared. It has a few conditions
● One's dues are fully repaid.
● It is actually a bureau reporting error
● If the lender willingly approves the account status to the relevant status
Remember to receive your No Dues Certificate (NOC) after repaying your dues. This is important for any future errors or delays in account status updates within 45 days. It serves as official legal proof that your account is closed with no remaining dues. Dispute evidence is important; without it, your error dispute remains invalid. It is a mechanism to protect your CIBIL score and prevent future rejections by lenders.
The best answer to “how to clear written-off in CIBIL" is to repay the full amount.
1. Repay the full amount.
This is the most acceptable way to protect yourself from further delinquencies or legal actions.
● Analyse your credit report to obtain details
● Contact your lender or bank to pay the full amount or a one-time settlement offer. However, the latter may raise eyebrows because it shows up as “post-write-off settled” or "settled."
● Request the total outstanding amount.
● Clarify the principal amount, interest, and penalty charges.
● Pay the entire amount.
Post settlement of the dues, ask for confirmation from the lender and ensure that the lender has updated the status of the account at the credit bureau. Though the record may not be deleted, it is very positive for any future lender if the written-off account is fully paid off.
2. Get the NOC
The steps on how to clear written-off in CIBIL don't end here. After making the payment, one must always obtain the NOC. The NOC would serve as official proof of the following:
● Repayment of the loan.
● There is no outstanding balance.
● Closure of the account has been confirmed by the lender.
This certificate becomes very handy if:
● CIBIL fails to update the report.
● Any dispute happens in the future.
● Incorrect balances keep coming up.
Maintain the certificates both physically and digitally.
3. Determine if There Is an Error Regarding Written-Off Status
At times, lenders or credit bureaus provide incorrect data. Some errors include:
● Outstanding balance reported incorrectly
● Closed account still appearing to be open
● Written-off reporting error
● Duplication of the account.
● Mismatch in the identification
Always review your CIBIL report thoroughly.
After all this, ask your bank to update the account status in the CIBIL report and keep an eye out for any change in the status. Otherwise, you can raise a dispute or are liable to raise complaints with the RBI. Remember not to pay on the phone, ask for a written offer, verify the payment channel before proceeding, and ensure they present an NOC to you.
How to clear written-off in CIBIL if it is an error
In case of incorrect reporting of the written-off status, a formal dispute can be raised.
Step 1: Obtain Your Latest Credit Report
Acquire your latest credit report and find the incorrect information.
Step 2: Gather Proof Documents
Collect proof documents, including:
● NOC
● Loan closing letter
● Acknowledgment from the bank
● Receipts
● Confirmation of settlement
Step 3: Raise a Dispute
Raise a dispute with the credit bureau, website, or lender along with the documentation.
Step 4: Process of Verification
The credit bureau communicates with the lender to verify the details.
Step 5: Rectification and Update
In case of validation of the dispute, rectification takes place. Periodically check your report till your changes show up.
What Happens After Clearing a Written-Off Loan?
Many believe that the written-off tag disappears after the loan is paid off.
However,
● The repayment will be recorded first.
● The remarks on the account may be changed.
● The historical record generally remains, even after 7 years.
● It will still be visible to future lenders that you had problems repaying the account.
However, it is much better to clear the written-off status compared to not having cleared the account at all. So act quickly to follow the steps on how to clear written-off in CIBIL.
How to increase CIBIL score after I clear written-off in CIBIL
How to clear written-off in CIBIL is just the first step towards recovery. You will have to improve your credit profile.
Make All EMI Payments on Time
Payments being up-to-date are considered one of the most reliable signs of responsible use of credit facilities. Always remind yourself or automate the payment process if possible.
Reduce Credit Utilization
Do not utilize your credit card above 30% of the total credit limit of the card. Reduction in utilization is a sign of better financial discipline.
Do Not Apply for Credit Too Often
Applying for too many loans within a short time span may lead to the assumption that you face some kind of financial problem. It is best to avoid unnecessary hard inquiries.
Maintain Old Credit Accounts
If you have old credit facilities in your name that have a good payment history, maintain them like your old accounts to present valuable credit history and activity. This increases your credit age and experience, which is important for your CIBIL score, instead of discarding or closing the old accounts.
Use Secured Credit Products
In case you find it hard to receive regular credit facilities, it is recommended to consider the following instruments:
● Secured credit cards
● Fixed Deposit credit cards
● Small secured loans
Check Your Credit Report Regularly
Checking your credit report regularly is a healthy financial habit, which helps you identify fraudulent activities and raise disputes for errors, like duplicate accounts.
How to avoid written-off status
It is better to avoid written-off status rather than following the online steps on “how to clear written-off in CIBIL”.
Create a realistic budget.
Track income and expenses carefully to ensure EMI payments remain manageable
Build an emergency fund.
Unexpected emergencies such as medical emergencies or job loss can disrupt repayment plans. It might sound counterproductive to keep cash sitting in a bank account while you carry a loan balance, but the security it provides makes perfect sense once you put it into practice."
Communicate with lender early.
Once you become a non-performing asset, don't stay silent. Take the first steps and be proactive by contacting the lender before you miss further payments. They may provide restructuring options, temporary relief programs, one-time settlement, and extended repayment schedules.
Avoid Overborrowing
Other simple methods include avoiding overborrowing. Only borrow with a realistic plan if you can manage your debt-to-income ratio, do not anticipate any future obstacles or expenses, or if you already have enough funds to pay back with a guarantee.
Set alerts or auto-debit.
Set up calendars, payment alerts, or auto-debit to make sure you don't miss any due dates indirectly or unknowingly.
What happens if I don't resolve the written-off status?
A written-off status, if kept unresolved, intensifies the delay as you still owe the money.
Continued recovery actions
You might witness continued recovery or collection visits or calls.
Lower credit score
Your credit score can plummet to 550.
High Interest Rates
You are more likely to be rejected, and, in rare cases, you might be approved with much higher interest rates than the standard market rates.
Rejection for a loan or credit
Most banks, NBFCs, and financial institutions automatically reject your application with a written-off status.
Legal Obligations
They may file a lawsuit, most commonly called a civil suit, leaving you bankrupt in a rare case.
Growing outstanding balance
All that debt, fees, interest, and penalties continue to accrue into larger sums, leaving you with compound interest and a burden of debt and stress.
Long-term appearance of written-off status
A written-off status can be tagged for 7 years even after resolution, and banks may access that part of the history even after the 7-year CIBIL threshold.
Conclusion
Understanding the written-off meaning in CIBIL is crucial for maintaining a strong credit profile. Unlike popular belief, a written-off status doesn't mean that the loan has been forgiven or erased. It is just the bank's proceedings and account clearance process for redundant accounts and debts that are unlikely to be recovered. It should be understood as an accounting action rather than debt forgiveness. There is no such thing as debt forgiveness in legal or financial frameworks.
If you are clueless about how to clear written-off in CIBIL, the one and only recommended option is to pay your outstanding balance in full. Only this way are you completely clear of your dues, any marks in CIBIL, and any scrutiny from lenders or banks in the future. Obtaining a No Dues or No Objection certificate is an important legal and evidential
step in this process. Despite full repayment, a written-off status remains accessible for a long time, even after the 7-year CIBIL threshold.
FAQs
1. What is a Non-Performing Asset?
A Non-Performing Asset (NPA) is a loan account in which repayments are overdue after the stipulated period of inactivity. It implies that the borrower has stopped making regular payments, and hence, it poses a credit risk to the lender.
2. Will clearing a written-off loan help raise my CIBIL score?
Yes. Although it cannot erase the past, settling the debt is seen as positive behavior that could be helpful in regaining the credit score.
3. How long does it take for a written-off account to fall off my credit report?
A written-off account can continue to affect your credit report for some years to come. It can stay for 7 years, and even after that, it is accessible to banks.
4. Is it possible to get loans with a written-off account?
Yes, although this is very difficult, as most banks regard such an account as a high-risk marker. The loans, if any, approved might be subject to more stringent eligibility criteria and increased interest rates.
5. What is better: settled, closed, or written off?
● Closed is better than any of them; it means that the account is paid in full. It might be taken as neutral or positive.
● Settled stays in the middle, which means that only a partial negotiated final amount is paid. It always shows in the credit report as negatively settled.
● Written-off has the worst possible impacts, drops your score below 550, and is attributed after 180 days of inactivity.
6. What is post-written-off settled?
This is a status update, which means that you paid a partial settlement after your account was written off due to 180 days of inactivity.